Total Articles 231+

Clean energy

Focuses on India’s transition to renewable energy sources like solar, wind, and hydro, aiming to reduce carbon emissions and promote sustainable power generation.

Showing 12/21

13 Oct 2026

Oct 13, 2026 | Kolkata As India transitions towards a green economy, green skills will be presented as a pathway to sustainable occupations. But after graduation, will the certificate be merely the finishing school or will it lead to good jobs, wages, and career progression? Looking beyond enrolment, this paper explores ways in which training providers, employers, and policymakers can connect green skills to livelihoods by addressing learnings beyond course completion. Summary :Green skills will play a critical role in India’s sustainable development, but a certificate will not guarantee employment. The focus will need to turn to the jobs obtained and the wages earned, as well as safety and career progression. Employers, institutions, and government will need to collaborate to ensure that green skills lead to sustainable, fair, and economically workable occupations. Can Green Skills Training Guarantee a Sustainable Career? Green skills training will prepare learners for emerging opportunities in renewable energy, sustainable farming and waste management. However, completing a course will not automatically guarantee employment or financial stability. Graduates will need practical experience, relevant job opportunities and fair working conditions to build sustainable careers. The focus must therefore extend beyond certificates to the livelihoods they help create. Introduction: From Learning Green Skills to Earning a Living Solar panel installation, sustainable farming, waste recycling, and energy auditing will soon be among India’s hot careers. The opportunity will be reassuring to many, as a certificate will be presented as a gateway to a sustainable livelihood. But after graduation, where will the solar panel installers, sustainable farmers, waste recyclers, and solar panel installers obtain jobs? What will they earn? How safe will the working conditions be? And will they be able to progress? While a degree or certificate will be a fulfilling milestone and a useful credential, it will not be a guarantee of a job offer. Employment will still require prospecting, proving competence and competency, negotiating wages, and learning the ropes on the job. We will therefore need to focus beyond the number of people trained and look at their livelihood outcomes after graduation. India’s push towards renewable energy, efficiency, and effective waste disposal will create demand for various occupations. But the green skills agenda will need to prioritize linking learners to jobs while considering local labor-market realities. We will need to think through such questions as: Will the training lead to relevant employment? Will the wages be adequate? Will the working conditions be safe? And will there be opportunities for career progression? The certificate will be merely the beginning. What Are Green Skills? Green skills will encompass the knowledge, expertise, and skills that will be needed to support an environmentally sustainable and resource-efficient economy. The skills will include technical competencies, such as solar panel installation and electric vehicle maintenance, and core skills, such as digital literacy, communication and collaboration, and project planning. The skills will be relevant across professions, from electricians and farmers to truck drivers and plumbers, as the occupational requirements for many will change over time. Various jobs will need to be made greener, including electricians, gardeners, construction workers, and transport drivers. Green skills will therefore need to be developed for both emerging jobs, such as solar panel installers, and established occupations, such as plumbers and car mechanics. We will need to think through the job requirements when designing the curriculum, such that construction workers learn about energy-efficient materials, car mechanics get the skills to service electric or hybrid vehicles, and plumbers learn about water harvesting systems. Why the Certificate Will Only Be the Beginning? A certificate will show that the graduate has completed a course, but employers will need to figure out whether the trainee can perform specific tasks and duties safely and competently. The skills bought may not always be directly applicable, and theoretical knowledge may not be sufficient if the job requires working with equipment and materials. Some training centres may also not have the infrastructure and ability needed to ease the skills needed for a specific occupation. Graduates may also find that the local labor market does not value the skills they have got or that there are no jobs that match their qualifications. This is not to dismiss the value of certificates but to acknowledge that the employability of the graduate will depend on the quality of training and the demand for the skills in the local labor market. Apprenticeships, practice, and field schools will therefore be useful in linking skills to specific occupations. Employers will need to find the entry-level competencies needed for the target jobs and advise on the learning strategies best suited to building those skills. The training program will also need to recognize its limitations and avoid misleading the trainees into thinking that the certificate will guarantee employment. The placement of learners will therefore need to be considered when producing the curriculum, such that it builds skills for specific occupations. Unless there is a confirmed placement, a training curriculum should not position itself as a guaranteed gateway to employment. Where Will the Green Jobs Be? Solar panel manufacturing and installation, sustainable farming, and waste collection and recycling will create employment opportunities. Other careers likely to appear include energy auditors, water harvesters, and environmental analysts. The occupations will be found in diverse economic sectors, including construction, transport, and agriculture. There will be variations in the type and number of jobs depending on the location, with urban areas likely to lead the way in some areas, such as rooftop solar panel installation, while rural towns and cities will lead in others, such as agriculture. A local assessment will therefore be needed to show the green jobs that are likely to appear and the skills needed for each. Industry players will also need to engage local employers and show the vacant positions, the recruitment criteria, and the entry-level skills and competencies needed. Policymakers and employers can support the process by providing insights into the most promising green jobs in various localities. The assessment will also need to consider the opportunities that might arise at various levels, such as entry-level jobs for people with only basic skills or supervisory roles for those with more experience and advanced skills. India’s Green Skills Challenges India’s shift towards a green economy will create employment opportunities but will also require that the skills being gotten match the local labor-market needs. While some will be able to secure jobs and advance their careers using the skills, others will be unemployed or may need to look for alternative careers. Green skills will therefore need to be developed with a focus on linking the learners to jobs while addressing their diverse needs. Access to the training programs will also be important, and factors such as distance to training centres, gender, and disability (physical and intellectual) will need to be considered. Lack of transport, poor road safety, and the absence of hostel facilities may discourage learners from enrolling and completing the courses. Similarly, inadequate consideration of the needs of people with disabilities may limit their participation. The gender dimension will also need to be considered, including the opportunity to take up certain occupations and address any cultural challenges that could influence the working conditions. Language skills will also be needed, depending on the occupation, and learners will need to understand instructions and the working conditions, especially if they are likely to be unsafe. It will also be important to share information about the working hours and conditions, as well as the wages and career progression, so that they make an informed decision about joining the program. We will not be able to help address the employment challenge if we mislead the learners into thinking that a certificate will guarantee them a well-paying job when there are no opportunities. Following the Graduate: What Will We Measure? It will be important to follow up on the graduates to figure out whether the training program was successful in linking them to a sustainable livelihood. First, we will need to collect information on the graduate’s employment status and the length of time it took for them to secure a relevant job. Someone who takes only a few months to get employed will have a dissimilar experience from someone who is unemployed. This information will enable us to show the link between the training program and the labor market. The information on the wages will also be important in showing the value proposition of the training program. We will need to ask the graduates to provide details on their salaries and their satisfaction with the working conditions and opportunities for progression. If a graduate can secure a well-paying job with good working conditions, we can use the information to promote the training program as a pathway to sustainable livelihood. We will also need to consider the differences in the wage levels, length of service, and other factors, such as whether the employment is permanent or daily. Other indicators to consider include the relevance of the job to the training course, the provision of safety equipment, and the working conditions and terms of employment. Employers will need to provide details on whether the workers are provided with contracts and the benefits they are entitled to as employees. Where possible, efforts will also need to be made to ensure that the information collected is disaggregated based on gender, location, and disability so that we can show the specific employment needs of various groups. The findings will also need to consider the graduates who are unable to secure employment and their perspectives on the shortcomings of the training program in helping them get a job. The follow-up will need to be done at specified intervals, such as every three, six, and twelve months, and can be done through surveys, interviews, and employer feedback, where possible. The graduate will also need to understand the type of information being collected and its purpose and have the option to decline if they are not comfortable sharing the information. The goal of the follow-up should not be to blame the graduate for being unemployed but to understand the extent to which the training program and the overall system did not support them in securing a relevant job. What Role Does the Employee Play? Employment relations will be key to ensuring that green skills lead to sustainable livelihoods. Training institutions will need to engage prospective employers when producing the curriculum, such that the course aligns with the skill needs of the local labor market. Employers can also advise on the most right learning strategies to use in developing the skills, such as apprenticeships and field schools. The input will be critical in ensuring that the training program meets the skill expectations of the local employers and that the graduates are not wasting their time and money on irrelevant skills. The engagement will need to go beyond signing partnership agreements, hosting the opening, and closing ceremonies of the training programs. Employers will need to support the process by providing the necessary equipment and making apprenticeships available, where possible. They will also need to acknowledge the value of their input into the training program and treat the graduates fairly and respectfully. Unless the training institution has sufficient knowledge of the local labor market, the skills being taught could be irrelevant, and the employer will withstand the worst of the disappointment when the graduate turns out to be unprepared for the job. The employer will also need to take a realistic view of the recruitment needs and not promise jobs that they do not intend to offer when the time comes. The collaboration should be based on realistic expectations on both sides, with the employer recognizing that the training program will help both the worker and the business. Employers in small businesses will also need to consider engaging in shared apprenticeships, where possible, rather than host in-house training programs that could be too expensive to sustain. Local associations and government agencies will need to ease the process of bringing together the employers and the trainees. The strategy will be useful in ensuring that the training aligns with the skill needs of the local economy while also addressing the limited resources of the individual employer. Women, Informal Work, and Fair Wages The green transition will only be truly sustainable if it supports fair development and enables everyone to derive maximum benefit from the opportunities it creates. For instance, women will need to be recruited into mainstream employment, and working conditions will need to consider their specific needs, such as safe working conditions and flexible working hours, where possible. Training institutions and employers will need to recognize the challenges facing women as they join the workforce, including personal safety and general working conditions, such as the provision of amenities. The informal sector will also need to be considered, as many potential workers will be using in the informal economy, where they lack the social security and financial benefits of formal employment. They will need to be supported to transition into the formal sector, where they will be able to enjoy safer working conditions and access a wider range of opportunities, such as skills upgrading, formal contracts, and better wages. Training will play a role in empowering the informal workers by helping them understand their rights and equip them with new skills that will increase their capacity and bargaining power. Fair wages and safe working conditions will also need to be prioritized if the informal workers are to transition into the formal sector. The opportunity to join the formal economy should not be limited to those with specific skills, as most of those working in the informal sector are doing so out of necessity. Policies will need to be put in place to support informal workers through incentives, such as reduced taxes and access to credit, and encourage employers to offer formal employment to their workers. What Can Training Institutions and Government Do? Training institutions will need to provide clear information on the training course, including the length, costs, assessment criteria, and types of jobs the graduate will be able to secure after completing the program. They will need to recognize that a certificate does not guarantee employment and should discourage prospective learners from enrolling if there are no job opportunities for the graduates. The curriculum will need to be reviewed on a regular basis based on the feedback from past graduates, current learners, and employers, as well as general considerations of the quality of training. Government agencies and local authorities will need to help the process of connecting the training institutions with employers, provide relevant data and insights on the local economy, and encourage and support quality apprenticeships and effective career guidance. They will also need to support small businesses in engaging in quality apprenticeships that will help both the employer and the employee. Reporters will need to ensure that the information on vocational training is presented in a responsible manner that highlights the dissimilar stages of the training journey and makes it clear what the graduate will be able to achieve at the end of the program. Independent evaluation will also be needed to ensure that training institutions are not misleading the public by overestimating the benefits of the training program. The independent assessment should be used to review the courses that do not lead to sustained employment and consider ways of improving those that are useful but have limited impact, such as by incorporating more practical aspects into the curriculum. The evaluation will also be useful in comparing different training programs to decide which are more beneficial to the graduate. The Graduate’s Voice We will need many indicators to understand the employment outcomes of the green skills training programs. But we will also need the voice of the graduate, who will provide a personal perspective on the situation and explain the context in which the indicators were achieved. Someone will be excited and grateful to have been recruited, while another will be disappointed and frustrated with the overall outcome. The graduate will also provide an explanation of why the outcome was achieved, such as mentioning that the apprenticeship helped them get the job, that the local economy did not support their recruitment needs, or that the employer did not value their skills. The insights will be critical in helping us name opportunities for improvement, such as encouraging those who did not secure a relevant job to consider alternative careers. Some of the graduates will need to be supported to upgrade their skills so that they can move from an entry-level position to a more advanced role, while others will need to be informed about the working conditions and other considerations, such as the distance to the workplace or the ability to afford to work in the informal sector. The feedback will therefore need to be considered when reviewing the overall approach to vocational training. Graduates will need to be encouraged to become partners in ensuring that vocational training contributes to sustainable livelihoods. Their views and experiences will need to be considered when interacting with potential employers and designing training programs, with those who have had a positive experience emphasising their success while those who are disappointed will challenge us to improve the overall system. Honest feedback will be important in empowering future graduates to make informed decisions about vocational training. Conclusion: Green Jobs Must Deliver Green Futures Green skills will open the door to a wide range of occupations, including solar panel installation, sustainable farming, and waste recycling, among many others. But the certificate will only be the beginning of the journey, and the focus will need to shift to helping the graduate secure a relevant job, obtain competitive wages, and move up the career ladder. We will need to measure the success of green skills training in terms of the livelihood outcomes of the graduates and not just the number of people trained and certified. Are the graduates being recruited into relevant occupations? Are the wages and working conditions satisfactory? Will the job allow the worker to grow professionally? Will women and other disadvantaged groups be given equal opportunities? Are the employers satisfied with the skill levels of the new hires, and will the workers be able to sustain the jobs? These are some of the questions we will need to consider in assessing the impact of green skills training. References and Sources 1. International Labour Organisation (ILO) https://www.ilo.org/ 2. International Energy Agency (IEA), 2024 https://www.iea.org/ 3.Ministry of Environment, Forest and Climate Change, Government of India https://moef.gov.in/ 4. Skill Council for Green Jobs (SCGJ) https://sscgj.in/ ...Read more
06 Oct 2026

6 October, 2026 | Kolkata India wants to turn crop residue from a seasonal pollution problem into a rural fuel economy. But the real test begins after harvest: who collects the straw, who pays the farmer, who bears the transport cost, and what happens to the soil when the residue leaves the field? SummaryIndia already has hundreds of Compressed Biogas (CBG) projects either operational or under development, while government policy is gradually pushing biomethane into the transport and gas ecosystem. But crop residue is not an ordinary raw material. It is available only during a short harvest window, varies in moisture and quality, can be costly to collect and transport, and plays an important role in maintaining soil health.This makes the economics of CBG more complicated than simply building more plants. The success of India’s CBG economy will depend on whether farmers can reliably move crop residue from fields to processing plants at a cost that works for farmers, aggregators and plant operators alike - without creating new environmental costs in the process.The real question, therefore, is not how many CBG plants India can announce or build but whether India can make crop residue economically valuable without making its removal financially or ecologically costly. Can India’s Crop-Residue Economy Work at the Farmgate, Not Just at the Plant Gate? After the paddy harvest, the clock starts ticking. A farmer in Punjab or Haryana may have only a narrow window before the next crop has to be planted. The straw left behind is bulky, difficult to handle and expensive to move. Burning remains attractive precisely because it offers a fast solution to a time-sensitive problem. That is what makes Compressed Biogas (CBG) such an interesting proposition. Instead of treating paddy straw as something to dispose of, a CBG plant can treat it as a feedstock. Straw is collected, baled, transported and processed through anaerobic digestion. The resulting biogas is upgraded into biomethane and compressed for use as fuel, while the process can also generate organic manure. On paper, it is an elegant circular-economy story. But the field is much less tidy. The straw has to reach the plant on time and meet quality requirements. Trucks have to travel. Bales have to be stored. Farmers and aggregators need to be paid or compensated. The plant needs to remain operational. The gas needs a reliable buyer. Digestate needs to meet applicable standards and find a credible agricultural use. And all of this has to happen within a highly compressed agricultural season. That is the farmgate test. India’s CBG Sector Is Moving Beyond the Pilot Stage India’s policy architecture is no longer treating CBG as an experimental fuel. The Sustainable Alternative Towards Affordable Transportation (SATAT) initiative was launched in 2018 to build an ecosystem for producing CBG from waste and biomass. Oil and gas marketing companies including IOCL, BPCL, HPCL, GAIL and IGL have been inviting producers to supply CBG, while the government says long-term offtake agreements at assured prices are being executed. The policy push is becoming stronger as well. India’s CBG blending obligation has entered its mandatory phase, with a requirement of 3% for FY2026–27, rising to 4% in FY2027–28 and 5% from FY2028–29. As of 27 January 2026, the GOBARdhan portal reported 189 functional CBG projects across India. Uttar Pradesh had 37, Gujarat 25, Haryana 20, Karnataka 20, Maharashtra 20 and Punjab 10. That points to a rapidly emerging industry. But there is an important distinction: A functional CBG plant is not automatically a successful crop-residue supply chain. A plant can have the technology, an offtake agreement and the ability to produce gas. The harder question is whether it can secure enough suitable biomass, at a workable cost, year after year. THE SEASONAL RESIDUE FLOW Create a horizontal seasonal flow: Paddy harvest → Straw collection → Baling → Village aggregation → Storage → Transport → CBG plant → Biomethane → OMC/fuel buyer Under each stage, show the potential friction point: 15 –20 day harvest window | Moisture | Quality | Farmer payment | Storage loss | Transport cost | Downtime | Methane loss | Offtake Crop residue is a moving, seasonal supply chain - not a static national tonnage figure. Punjab Shows Both the Promise and the Problem Punjab is a natural laboratory for this question. The state has been promoting both in-situ and ex-situ crop-residue management. ICAR reported in September 2026 that Punjab has around 31.76 lakh hectares under paddy and nearly 20 million tonnes of straw generation, while stakeholders have been calling for stronger biomass aggregation, transportation, storage and assured offtake. That discussion reveals where the challenge is moving. The question is no longer simply how to convince farmers not to burn residue. It is how to build a system capable of handling the material once it is removed from the field. Punjab Energy Development Agency currently lists 57 allocated CBG projects, with a combined capacity of about 815.68 tonnes per day, based on paddy straw and other agricultural residues. Six projects, totalling around 107.48 tonnes per day, are operational, while another five projects with a combined capacity of 37.5 TPD are expected to become operational during FY2026–27. That immediately raises a larger question: Where will all the straw come from? Following the Straw to Lehragaga One of the most useful case studies is the Verbio biorefinery at Lehragaga in Sangrur district, Punjab. The plant began producing biomethane from agricultural residues in 2022. The company says the facility was designed to process around 100,000 tonnes of agricultural residue annually, with BioCNG production capacity of up to 33 tonnes per day, alongside large-scale production of humus fertiliser. Its gas is supplied into IndianOil’s retail network in Punjab. This is precisely the kind of plant the investigation should follow. Not because it should automatically be presented as a success story, but because it allows the reporting to examine the entire chain. Where does the straw come from? How far does it travel? Who aggregates it? What does the farmer actually receive? Is the farmer paid for the straw, or does the economic benefit primarily come from free collection? How much does baling cost? What happens when the straw is wet? What happens when the plant needs more feedstock than nearby farms can provide? What happens when the plant is not operating? And what happens to the material that comes out at the other end? Verbio has described its model as providing farmers with free straw collection while creating rural economic value. That is useful evidence. But “free collection” is not the same as a measured increase in farmer income. The reporting therefore needs the actual ledger. The Farmer’s Income Cannot Disappear Behind the Word “Waste” This is where the CBG story needs greater precision. Crop residue is often described as waste. For the farmer, however, it is not necessarily worthless. Depending on the farming system, residue can be incorporated into the soil, used for livestock-related purposes, sold into biomass-energy or industrial markets, or directed towards other value chains. In some cases, it may also represent a cost rather than an income opportunity. The relevant economic question is therefore not: “How much does a tonne of straw cost?” It is: “What is the farmer’s net position after the residue leaves the field?” That calculation should account for: payment received for residue, if any;baling and handling arrangements;transport responsibility;time saved;machinery costs avoided;alternative value of the straw;impact on field preparation;possible soil-nutrient replacement costs;and the reliability and timing of payment. A farmer receiving ₹X per tonne is not necessarily better off if removing the straw creates ₹Y of additional costs elsewhere. The article should therefore avoid using a headline straw price as a proxy for rural prosperity. FARMER NET-INCOME CARD FARMER NET OUTCOME Straw payment+Collection / handling savings+Avoided field-management cost−Transport or other deductions−Nutrient / soil-management cost=NET FARMER VALUE Use actual numbers from one documented farmer or FPO account. Do not present a modelled figure as observed farmer income. The Soil Cannot Become the Invisible Stakeholder There is another side to removing residue from the field. ICAR’s recent crop-residue work continues to emphasise in-situ management, including the incorporation of straw into soil. Its field programmes have highlighted potential benefits related to soil organic carbon, fertility, water conservation and nutrient retention. That creates a genuine competing viewpoint. One argument says: Take the residue away and turn it into fuel. The other says: Not all residue should be removed because some of it belongs in the soil. The article should not automatically choose one side. The more useful question is: How much residue can be sustainably removed from a particular farming system without undermining soil health? That answer will not be identical everywhere. Soil type, crop rotation, irrigation, organic-carbon levels, residue quantity, local machinery and competing uses can all influence the answer. A CBG plant therefore cannot simply define its feedstock requirement and assume surrounding fields can sustainably supply it. The field has an ecological budget too. The Logistics Problem Starts Long Before the Plant A bale of straw is not a pipeline commodity. It has to be collected from scattered farms and moved to aggregation points before reaching the plant. That creates a collection-radius problem. The farther a plant has to travel for its feedstock, the more complicated the economics become. The physical chain may look like: Field → Baler → Tractor/trailer → Aggregation point → Storage → Truck → Plant Every additional movement consumes time, fuel and money. There is also a seasonal mismatch. The plant may need feedstock throughout the year, while farms produce most of their straw within a narrow harvest window. Storage therefore becomes part of the business model. The investigation should seek: daily weighbridge records;bale counts;source-village records;average collection distance;storage duration;rejected loads;moisture readings;quality specifications;transport bills;and plant feedstock inventories. If those records cannot be provided, that absence is itself relevant evidence. Moisture Can Decide Whether the Economics Work Biomass is not uniform. Moisture affects its weight, storage behaviour and usable energy content. Poorly managed biomass can deteriorate during storage and create operational problems. That means two farmers delivering apparently similar bales may not be delivering the same usable feedstock. This makes moisture and quality rejection central to the investigation, not minor technical details. The plant’s contract should establish: What moisture level is acceptable?What happens when a load exceeds it?Is the farmer penalised?Is the aggregator penalised?Who pays for rejected material?Is the material returned?How frequently does rejection occur?How is moisture measured? A feedstock contract that looks attractive on paper can behave very differently once quality deductions enter the calculation. The Gas Is Only Half the Story CBG is not the end of the process. The plant also produces digestate or organic manure, creating the possibility of another circular-economy loop. Residue enters as agricultural feedstock. Gas leaves as fuel. Digestate can potentially return to agriculture. But that loop only works if the digestate is safe, compliant, usable and actually accepted by farmers. A previously reported case at the Lehragaga plant highlighted moisture-related concerns around manure specifications, showing why the by-product can become a commercial and regulatory issue rather than an automatic benefit. The investigation should therefore seek digestate analysis, not simply photographs of manure being loaded onto tractors. It should examine: moisture;nutrient content;contaminants;compliance with applicable standards;storage;farmer uptake;price;and actual field application. The circular-economy claim is incomplete if the digestate has nowhere credible to go. Methane Leakage Is the Other Side of the Climate Claim CBG can only deliver its intended climate benefit if the entire system performs properly. Methane is the product being captured and sold. It is also a powerful greenhouse gas if it escapes before capture, during processing, storage or upgrading. That makes methane leakage one of the most important evidence gaps in the story. A production number tells us how much methane became a commercial product. It does not automatically tell us how much methane escaped. The investigation should therefore ask for: Leak-detection methods, testing frequency, maintenance records, fugitive-emission data and corrective-action logs. If methane-leak testing is unavailable, the article should say so. Missing measurement should never be replaced with a generic claim that biogas is “clean”. The climate claim needs a boundary, a baseline and a measurement method. The Buyer Matters as Much as the Farmer The CBG business does not end when gas leaves the plant. Someone has to buy it. SATAT provides a potential route through oil and gas marketing companies, while the CBG blending obligation creates a growing policy-driven demand signal. But the reporting should still establish: Who is the actual buyer? What does the contract guarantee? What happens when production falls below contracted volumes? Who bears quality risk? How is the price determined? What happens if the plant cannot produce for several days? This is where the distinction between an announcement and an operating business becomes critical. A plant with a signed offtake agreement is not the same as a plant delivering gas reliably every day. Downtime Is the Number Nobody Wants to Headline A CBG plant can have impressive installed capacity and still produce far below its theoretical maximum. The reasons can range from feedstock shortages and equipment failures to maintenance, quality problems, transport disruptions, storage issues or market constraints. That is why the investigation should calculate: Actual uptime = Operating hours ÷ Available operating hours It should then compare: Installed CBG capacity with Actual average production That comparison is more informative than the nameplate number alone. The same principle applies nationally. India reported 189 functional CBG projects as of January 2026, but that figure does not tell readers how much each plant actually produces, how consistently it operates or what proportion uses crop residue as feedstock. Functional is not the same as fully utilised. CBG Is Not the Only Destination for Straw The market for crop residue is becoming more competitive. Straw can be directed towards CBG, biomass power, pellets and briquettes, biofuels and other industrial applications. The Commission for Air Quality Management has also directed Punjab and Haryana to increase the use of paddy-straw-based pellets or briquettes in brick kilns, with the mandated co-firing share rising to 30% from 1 November 2026, after 20% from November 2025. That means new CBG plants are entering a market in which multiple users may compete for the same seasonal material. This could benefit farmers. More buyers can mean more choices. But it can also create instability for plants that require predictable feedstock volumes. The investigation should therefore map the local residue market, rather than treating all available straw as if it automatically belongs to CBG. Perhaps the Answer Is Not One Technology This is where the story should resist a simple conclusion that CBG will “solve stubble burning”. ICAR’s work shows that in-situ residue management can reduce burning while supporting soil-related outcomes. Its work also stresses that machinery availability, maintenance and region-specific solutions matter. At the same time, ex-situ options such as CBG can create a market for residue that farmers otherwise struggle to manage. The stronger policy answer may therefore be a portfolio rather than a winner-takes-all technology race. Some residue can remain in the field. Some can feed CBG. Some can support industrial biomass demand. Some can move into other value chains. The right mix should be determined by soil science, economics, logistics and local conditions. Not by the number of CBG plants announced. What Would a Genuinely Working CBG Farmgate Model Look Like? A strong plant should be able to demonstrate at least ten things: 1. A defined collection radiusNot a vague reference to “nearby farmers”, but a documented sourcing geography. 2. Transparent farmer economicsWhat the farmer receives, what the farmer saves and what costs remain. 3. A functioning aggregation systemWho collects the bale, who owns it and who bears transport risk. 4. Quality controlsMoisture, contamination and rejection records. 5. High and documented plant uptimeNot just installed capacity. 6. Verified methane managementLeak testing and corrective action. 7. A credible digestate pathwayTesting, compliance, price and actual agricultural use. 8. A contracted buyerWith clear price, volume and quality terms. 9. Soil safeguardsEvidence that residue removal does not undermine local soil-health needs. 10. An independently checkable ledgerThe plant should be able to show what entered, what was produced, what was rejected, what was sold and what returned to agriculture. THE CBG ACCOUNTABILITY LEDGER Build a single-page dashboard connecting four stages: FARMGATE → PLANT → OUTPUT → FIELD Track: Farmgate Tonnes collectedFarmers coveredAverage collection distanceFarmer net valueTransport cost Plant Tonnes receivedRejected loadsMoisturePlant uptime Output CBG producedMethane leakageBuyer/offtake Field Digestate returnedFarmers using manureSoil indicatorNutrient balance Every number should carry a date, unit and source. The Documents Should Decide the Story The investigation should not depend on a company presentation deck. The reporting file should seek: feedstock contracts;farmer agreements;FPO and aggregator agreements;weighbridge logs;bale movement records;farmer payment records;transport invoices;moisture and quality-rejection logs;plant production records;downtime records;offtake contracts;methane-leak testing;digestate laboratory reports;fertiliser-compliance documentation;soil assessments;air-quality data;environmental permissions;pollution-control records;and maintenance records. If an operator refuses a document, record the request and the response. If a government agency holds the document, seek it there. If a number cannot be independently verified, label it accordingly. The reporting standard should remain clear: announced, commissioned, operational, maintained and measured are not interchangeable terms. A plant is not a success because it was announced. A capacity figure is not production. A contract is not delivery. And a climate claim is not an outcome until the underlying result can be measured. The Real Test Begins When the Harvest Ends The CBG story is often told from the plant backwards. Look at the digester. Look at the gas. Look at the cylinders. Look at the truck leaving with fuel. But the real story begins much earlier. It begins with a farmer standing in a field after harvest and asking what to do with the straw before the next crop goes in. If CBG gives that farmer a dependable alternative to burning—while protecting soil health, keeping transport costs manageable and creating a genuine economic return—then the technology becomes more than a clean-fuel project. It becomes rural infrastructure. But if the plant depends on expensive long-distance transport, inconsistent feedstock, weak storage, uncertain payments, low utilisation or an unproven digestate market, then the problem has simply moved from the field to the supply chain. And that distinction matters. India does not need more tonnes of theoretical biomass. It needs working contracts, working logistics and working economics. Punjab’s latest crop-residue discussions already point towards this next challenge: nearly 20 million tonnes of paddy straw, a growing network of CBG projects and an urgent need to solve aggregation, transportation, storage and assured offtake while replenishing nutrients where straw is removed. That is why the future of CBG will not be decided inside the digester alone. It will be decided at the farmgate. The Final Farmgate Test When the crop is harvested, does the residue become fuel, income and soil-safe value—or does it simply become another expensive material that someone has to move? That is the question the CBG economy must answer. And it should answer it with evidence—not projections. CAN THE MODEL PASS? FARMER — Is net value positive? FEEDSTOCK — Is supply reliable? PLANT — Is uptime proven? CLIMATE — Is methane leakage measured? SOIL — Is residue removal sustainable? A CBG model should not be called successful until there is evidence on all five.Primary Sources Ministry of Petroleum & Natural Gas (MoPNG) — Compressed Bio Gas / SATAT[https://mopng.gov.in/en/refining/compressed-bio-gas/1000]Punjab Energy Development Agency (PEDA) — Bio-CBG Projects[https://www.peda.gov.in/bio-cbg-compressed-piogas-projects.php]Ministry of New and Renewable Energy (MNRE) — Waste-to-Energy Schemes[https://mnre.gov.in/en/waste-to-energy-schemes/]MNRE — Bio-Energy Programme[https://mnre.gov.in/en/bio-energy-overview/]ICAR — Punjab Crop Residue Management Action Agenda[https://www.icar.gov.in/en/punjab-stakeholders-forge-integrates-action-agenda-crop-residue-management]Punjab Agricultural University (PAU) — VERBIO India, Lehragaga CBG Plant[https://pau.edu/index.php?DO=viewEventDetail&_act=manageEvent&dataE=datae&intID=7702]PIB / Ministry of Jal Shakti — GOBARdhan Scheme and CBG Projects[https://www.pib.gov.in/PressReleasePage.aspx?PRID=2222150&lang=1&reg=3]PIB / Ministry of Petroleum & Natural Gas — CBG Blending Obligation[https://www.pib.gov.in/PressReleasePage.aspx?PRID=1989226&lang=2&reg=48]CAQM / PIB — CBG and Crop Residue Management[https://www.pib.gov.in/PressReleaseIframePage.aspx?PRID=2187847&lang=2&reg=48]National Green Tribunal — Punjab Crop Residue Management Status Report[https://www.greentribunal.gov.in/sites/default/files/news_updates/Status%20Report%20by%20State%20of%20Punjab%20in%20OA%20No.%20632%20of%202023%20%28In%20Re%20News%20item%20published%20in%20The%20Hindu%20dated%2006.10.2023%20titled%20Pollution%20takes%20a%20front%20seat%20as%20Stubble%20Fires%20Spike%20in%20Punjab.pdf] ...Read more

06 Oct 2026

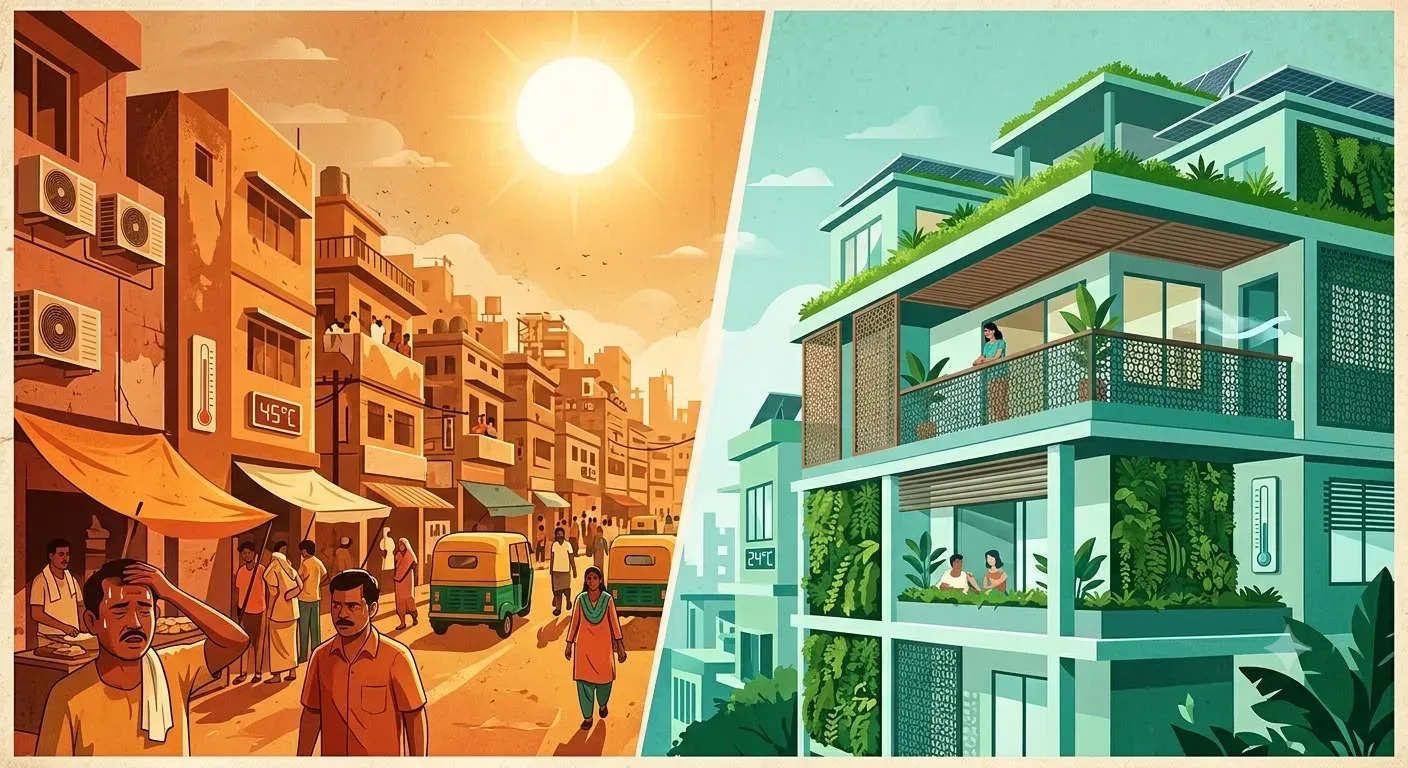
As temperatures rise in India, cooling is becoming essential to public health, household satisfaction, and economic productivity. But the growing popularity of air conditioning raises questions about electricity consumption, refrigerant emissions, affordability, and waste. We investigate how the Kigali Amendment and India’s Cooling Action Plan can support a cooling system that looks after people without compromising the environment.   SummaryWe explore how India’s growing cooling demand relates to climate change, public health, and energy usage. Through the Kigali Amendment and India’s Cooling Action Plan, we look at sustainable cooling technologies, refrigerant management, building design, and worker safety. The article highlights the need for affordable, accessible cooling without increasing environmental stresses.   Why is cooling becoming a necessity in India? As temperatures continue to rise, cooling is becoming an important part of everyday life in India. What once was seen as a luxury in many households is increasingly connected to health, productivity, and basic comfort. Heat affects people differently, but the risks can be particularly pronounced for older adults, children, outdoor workers, and people with existing health vulnerabilities. We often think of cooling as switching on an air conditioner or a fan, but the larger cooling system is far more complex. It begins with the design of buildings, the electricity consumed to use equipment, the refrigerants contained within cooling appliances, the workers who install and support them and the way equipment is treated when it is discarded. This wider perspective is important because cooling can protect people from heat but also contribute to environmental pressures. Air conditioners and refrigeration systems consume electricity and, if refrigerants escape, can contribute to global warming.  As more households, offices, hospitals, shops, and industries require cooling, we must consider how this demand can be met responsibly. We cannot simply focus on selling more appliances – we also must ask whether buildings can be designed to stay cooler, whether equipment will be efficient and whether cooling is affordable to the people who need it most. For us, the central question is not whether India needs cooling – it is how we can provide cooling without creating new environmental and social challenges.   What is the Kigali Amendment, and why does it matter? The Kigali Amendment to the Montreal Protocol was adopted in 2016 to reduce the production and consumption of hydrofluorocarbons, commonly known as HFCs. These substances are used in many refrigeration and air-conditioning systems. HFCs were introduced as a substitute for ozone-depleting substances, but many HFCs are powerful greenhouse gases. When they escape from air-conditioning equipment, they can contribute to global warming. The Kigali Amendment, therefore, is concerned with gradually phasing down the production and consumption of HFCs. India ratified the amendment in 2021 and follows a phased schedule for reducing HFC production and consumption. India’s schedule includes a first reduction landmark in 2032, followed by further reductions in 2037, 2042 and 2047. These are the scheduled phase-down landmarks, not evidence that the reductions have already occurred.  The amendment is important because it ties the cooling sector to global climate action – but simply substituting one refrigerant for another is not enough on its own. We also must ensure that new equipment is energy-efficient, safe to run and suitable for India’s climate and cooling needs. If a refrigerant has a lower climate impact but the appliance consumes too much electricity, the overall environmental benefit may be reduced. This is why refrigerant transition and energy efficiency need to move together. The Kigali Amendment gives us an international framework – the challenge is to translate it into practical action across India’s cooling economy.   How is India’s Cooling Action Plan addressing the challenge? India launched the India Cooling Action Plan (ICAP) in 2019 to address cooling demand with a broader, longer-term approach. The plan is aware that cooling is connected to several sectors – including buildings, transport, agriculture, healthcare, and industry. It aims to reduce demand for cooling, improve energy efficiency and encourage better technology, as well as supporting the development of skilled workers. The plan set targets for reducing cooling demand, refrigerant demand, and cooling energy requirements by 2037-38. These targets are intended outcomes and should not be described as achieved unless there is updated evidence. An important aspect of ICAP is its emphasis on reducing cooling needs before relying solely on mechanically produced cooling. If the buildings we occupy can limit the amount of heat we allow in, we may require less air conditioning to keep comfortable. The plan is also aware of the need for trained technicians – cooling equipment requires installation, servicing and maintenance, and refrigerants must be handled with care. Without skilled workers and suitable equipment, even efficient appliances can perform poorly or cause environmental harm. We should view ICAP as a framework that unites elements of the wider cooling system. Its success depends on co-ordination between government agencies, manufacturers, building designers, service providers, workers and consumers.   Why can a cooler room also mean a hotter grid? Air conditioners make indoor spaces more comfortable, but they require electricity to work. When many people start using cooling equipment, electricity demand can surge. This creates a challenge for power systems, especially during periods of extreme heat. If electricity supply relies on fossil fuels, increasing demand can also increase greenhouse gas emissions. This is why the phrase “a cooler room can mean a hotter grid” is important – cooling may protect us indoors, but the electricity we consume can have environmental consequences elsewhere. It would be wrong to interpret this as a reason to discourage people from using cooling when they need it – but it does highlight how we have to improve the overall system. Energy-efficient appliances can provide the same service but consume less electricity. Better building design can reduce the demand for energy-intensive air conditioning. Smart control systems and proper maintenance can help equipment function more effectively. We also have to consider electricity access and affordability. A household may have an air conditioner but avoid using it because of the cost of running it – in this case, appliance ownership does not mean the household has reliable access to cooling. A sustainable cooling system, therefore, has to reduce electricity consumption while ensuring that people can stay safe during extreme heat.    How can passive cooling reduce our dependence on air conditioning? Passive cooling refers to building design and other methods that seek to reduce heat indoors without relying solely on mechanically produced cooling. We can begin by looking at a few simple aspects: shading, ventilation, reflective surfaces and suitable building materials. The way a building is placed, its window size, the materials of its roof and walls – these can influence the amount of heat indoors. For example, external shading can reduce direct sunlight entering a room, and roof treatments may reflect sunlight to reduce the heat they absorb. Ventilation can also be used to create a flow of air when the outdoor conditions permit. These methods have proven to be helpful in many residential, educational, office and community buildings. They can also help reduce electricity costs by reducing the amount of time air conditioners have to work. However, passive cooling is not a universal solution, and its effectiveness varies depending on the climate, building design, humidity, air quality and use. While natural ventilation is ideal in some conditions, it may not be desirable in others. Natural ventilation, for instance, may not be desirable during periods of poor outdoor air quality or extreme humidity. Some hospitals and specialist workplaces also require controlled conditions – which cannot be achieved solely through passive measures. We should view passive cooling as one component of a broader system. Coupled with efficient appliances and thoughtful building design, it can help reduce cooling demand and contribute to indoor comfort.  What makes energy-efficient cooling important? Energy efficiency plays a crucial role in sustainable cooling, as it allows us to get the cooling we want while consuming less electricity. When comparing air conditioners or other equipment for personal use, we should pay attention to their energy-performance information rather than focusing on price, aesthetics or marketing claims. In India, the Bureau of Energy Efficiency offers energy labelling programmes for relevant appliances. These labelling guidelines can help us compare the energy performance of products, provided we look at the label for the product and its requirements. Of course, energy efficiency is not just about the appliance – it depends on several factors, such as the building’s design, the room’s size in which equipment will be used, its insulation and ventilation, as well as its maintenance. An air conditioner that is poorly installed or supported may not deliver the service we expect – in fact, dirty filters or blocked airflow can significantly affect its performance. We should also resist the assumption that the latest appliance will automatically be the right one for every space. Consumers need to understand the cooling requirements of their space, as well as the impact on operating costs, servicing requirements, and energy-performance characteristics. For hospitals, businesses and large buildings, the same principles apply – but on a larger scale, and with energy audits and maintenance playing a prominent role. The aim is not simply to reduce the amount of electricity we consume – but to provide the cooling service we want without consuming more than we must.   Which refrigerants are used, and what happens when they leak? Refrigerants are substances that are contained within cooling systems to help the transfer of heat. Different appliances use different refrigerants, and these substances vary in their environmental impact. Some have high global warming potential – others have a lower impact, but they also have safety, flammability, and operational considerations. These differences mean that refrigerant selection is a balance: it is not simply a matter of choosing whichever has the lowest climate impact. Equipment has to be compatible with a refrigerant, and technicians have to be trained to handle them. Leaks are a major concern because they can occur during equipment operation or servicing, transport or disposal. A refrigeration system may continue to function after a leak, but the system will be less effective and the refrigerant may escape. We need proper servicing records, leak detection and repair practices to reduce these risks. Technicians should have suitable tools and follow safety procedures for the specific refrigerant and equipment. We should also distinguish between refrigerant recovery and reclamation. Recovery refers to removing refrigerant from equipment, as opposed to simply releasing it into the atmosphere. Reclamation involves processing the recovered refrigerant to specific requirements for reuse. Both can be part of responsible refrigerant management, but they are distinct processes.   What happens to cooling equipment at the end of its life? The environmental impact of cooling equipment does not stop when it stops working. Discarded air conditioners, refrigerators and other appliances have materials that can be recycled or reused. They also have refrigerants and oils that may pose environmental and safety risks. Improper dismantling can expose workers to unsafe conditions and valuable materials will be lost when appliances are simply discarded without recovery. We, therefore, must consider the entire lifecycle of cooling equipment – from design and manufacturing to installation, maintenance, repair, collection, and end-of-life treatment. A responsible system would make it easier for us to return old appliances to proper collection points. Service providers and waste handlers must follow suitable procedures for recovering refrigerants and separating materials. Manufacturers can support this by considering product design, repair guidelines, spare parts availability, and take-back options were proper. We should not assume that an appliance has been responsibly recycled simply because it has been collected – we must look at the evidence about where it went, how the refrigerants were treated and which materials have been recovered.    How can district cooling support sustainable cities? District cooling refers to systems in which cooling is produced in a central location and distributed to several buildings through a network. Instead of each building having its own equipment for mechanically produced cooling, a shared system can be used for connected buildings. This can bring out opportunities for improved efficiency, maintenance and energy management depending on local conditions. District cooling can be a relevant model for large developments, commercial districts, hospitals, campuses, and other areas with intensive demand for cooling. However, it is not necessarily the best option for every city or neighbourhood – its performance will depend on factors such as building density, network design, local climate, electricity supply, investment costs, and the reliability of the system. We, therefore, must evaluate district cooling on a case-by-case basis. We need to look at how much energy it will use, what refrigerant it will rely on, how cooling is distributed, and whether the service will be affordable for the buildings and people it serves. District cooling is likely to be one component of sustainable urban infrastructure, but it has to complement other measures such as passive cooling and efficient appliances.   Why are hospitals an important part of the cooling conversation? Hospitals not only rely on cooling but also have significant cooling needs. Some spaces require controlled temperatures to support patient care, protect medicines, or operate equipment. This means reliable cooling is particularly important during extreme heat – but a cooling failure can impact patients, staff and hospital operations. At the same time, hospitals may have substantial cooling demands due to the long hours they run and the range of temperature-sensitive spaces. We should assess hospitals from both a public-health and an energy-efficiency point of view – the goal is not to reduce cooling indiscriminately, but to ensure that necessary conditions are kept while reducing unnecessary energy use. Hospitals must review their maintenance schedules, cooling arrangements, and energy performance. They must look at whether different areas require different cooling settings and whether building improvements can reduce heat gain. To understand the situation, we would have to speak to hospital administrators, maintenance staff, and healthcare professionals. Useful evidence would include indoor temperatures, equipment types, energy costs, maintenance schedules, and what resources exist for power interruptions. A specific hospital case should be based on verified reporting rather than assumptions – this would help prove how cooling decisions impact patients, workers, and costs in actual practice.   Who are the workers behind India’s cooling economy? Behind every functioning air conditioner or refrigeration system is a network of workers who install, repair, and keep equipment. Refrigeration and air-conditioning technicians are essential in the cooling transition – they handle refrigerants, inspect systems, identify leaks and perform repairs. As India moves towards new refrigerants and more efficient technologies, technicians will require updated training. We should not treat training as a one-off activity – workers have to have access to updated technical knowledge, appropriate tools and practical instruction. They also need safe working conditions and procedures related to refrigerant handling. Informal workers may face additional barriers such as the costs associated with training, limited access to equipment and uncertain employment conditions. A policy transition that ignores these may not be effective. We should include technicians in discussions on sustainable cooling, as their experience can help highlight practical problems such as recurring equipment failures, the availability of spares and difficulties in recovering refrigerants. A technician-focused field report could look at the refrigerants technicians typically handle, the tools they use, their training and the challenges they encounter during servicing. These details can help connect national climate targets with day-to-day working conditions.   How can we make cooling accessible without increasing inequality? As we develop our appreciation for new cooling technologies, we need to remember that access is not simply about availability. A cooling system may exist in a city, but it may not be affordable to nearby households. A hospital may have modern equipment, but maintenance costs may be too high. Technicians may receive training, but they may struggle to obtain recovery tools. We, therefore, must link cooling policy to affordability, infrastructure, and working conditions. For households, this can begin with better information on energy-efficient appliances, practical building improvements, and affordable servicing. For hospitals, it means protecting critical cooling while reducing unnecessary energy use. For businesses it means reviewing their equipment, refrigerant management, and the full cost of operating cooling systems. For policymakers, the challenge is to co-ordinate the various aspects of the system. We need building policies that reduce unnecessary heat gain, appliance standards that promote energy efficiency, refrigerant regulations that enable safe transitions and training programmes that reach the technicians who install and keep equipment. We also need reliable information – without data on electricity consumption, refrigerant leakage, equipment performance, indoor temperatures, and waste, it will be hard to measure whether systems are delivering the intended benefits. This is where independent research organisations, public-health experts, worker associations, and civil-society groups can contribute – their work can help us see the practical barriers that may not be clear in policy documents or industry announcements. Sustainable cooling must be measured not only through the technology being installed but also through the quality of services people are receiving, the environmental impact and the conditions in which workers are performing their roles.   What can we do at home and at work? Beyond national policy and industrial transformation, there are practical actions we can take to improve the way we use cooling. At home, we can reduce the amount of direct sunlight entering our premises by using right curtains, blinds, or shading. We can keep fans and air conditioners, keeping filters clean per manufacturers’ guidance and avoiding unnecessary use. We should use air conditioners following the needs of the room – rather than assuming lower temperatures will always be preferred. These settings can reduce electricity consumption while keeping our comfort. At work, we can review our use of fans or air conditioners, avoiding unnecessary energy use. If our workplace is air conditioned, we can check whether the temperature and airflow are proper and raise concerns if not. We can also consider the use of building materials and designs that help keep spaces cool without consuming vast amounts of electricity. As citizens, we should engage with building or appliance standards and energy labelling, encouraging our communities to embrace opportunities for passive and active cooling. We can support cleaner energy generation and promote responsible electricity use. We can ask questions about how our electricity is generated – is it cleaner? Is it cheaper? – and encourage our households and workplaces to reduce consumption where they can. We can request more information on waste management and refrigerant recovery – rather than assuming recycling happens automatically, we must demand accountability. This can help us assess whether our cooling systems are genuinely helping the environment. Finally, we can take care of our air conditioners and make sure they are supported, serviced, and repaired responsibly. This will ensure they are performing the most efficient service possible.   What should we check when evaluating a cooling system? To understand whether a cooling system is sustainable, we need evidence that covers its full lifecycle. Cool-home and cool-workplace checklist Refrigerant: What type is used, and what are its climate and safety characteristics? Energy performance: What energy label or performance information is available? Installation: Was the equipment correctly sized and installed? Service record: Is there a record of maintenance, repairs and leak checks? Recovery and reclamation: Is refrigerant collected during servicing or decommissioning, and where does it go? Disposal route: Is the appliance sent to a proper collection or treatment facility? Indoor temperature: Are indoor conditions suitable for the people using the space? Electricity cost: Is cooling affordable to use? Worker certification and training: Are technicians trained and equipped to handle the refrigerant safely? Cooling lifecycle Design and manufacture → Installation → Operation → Servicing and leak repair → Refrigerant recovery → Reclamation or proper treatment → Appliance collection and end-of-life processing This lifecycle approach helps us look beyond the appliance itself. It also gives consumers, businesses, and policymakers a clearer set of questions to ask when assessing cooling claims.   Conclusion: Cooling people without overheating the planet As we look towards India's cooling future, we need to recognise that cooling is no longer simply a question of comfort. It is connected to public health, energy security, employment, infrastructure, and climate action. The Kigali Amendment provides an international framework for reducing HFC production and consumption. India's Cooling Action Plan offers a broader approach that connects cooling demand, energy efficiency, refrigerant management, technology, and skills development. Together, they give us a starting point for rethinking how cooling is provided across the country. But the real test of this transition lies beyond policy documents and technology announcements. We need to understand whether households can afford to stay cool during extreme heat. We need to know whether hospitals can support reliable cooling when patients need it most. We need to examine whether technicians have the skills, tools, and working conditions necessary to manage refrigerants safely. And we need to set up whether cooling equipment is repaired, recovered, and disposed of responsibly. We also need to move away from the idea that one technology can solve every problem. Passive cooling can reduce heat entering buildings, efficient appliances can reduce electricity use, and district cooling may offer shared solutions in suitable locations. But each approach needs to be evaluated according to local conditions, costs, access, and environmental performance. Most importantly, we need to understand that sustainable cooling is not only about reducing harm. It is also about expanding access to an essential service. A household that cannot afford to use its air conditioner, a hospital struggling to support critical temperatures or a technician working without proper recovery equipment stands for a gap in the cooling system. We should therefore measure progress through more than the number of appliances sold or the refrigerants replaced. We need to consider whether cooling is reliable, affordable, energy-efficient, and accessible, while ensuring that workers and waste-management systems are included in the transition. The next time we enter a cool room, we should look beyond the temperature on the thermostat. We should ask how that cooling was produced, how much energy it needed, what refrigerant it uses and what happens when the equipment reaches the end of its lif Because the future of cooling is not simply about making our rooms colder. It is about building a system that protects people from heat without adding unnecessary pressure to the planet.   References and sources Ministry of Environment, Forest, and Climate Change — India Cooling Action Plan (ICAP) https://www.pib.gov.in/PressReleaseIframePage.aspx?PRID=1805795&reg=48&lang=2 Official framework for cooling demand reduction, refrigerant transition, energy efficiency, and cooling technology development. Press Information Bureau — India Cooling Action Plan      https://www.pib.gov.in/indexm.aspx?reg=48&lang=2 Government information on implementation, passive cooling in buildings and technician training. Press Information Bureau — Kigali Amendment to the Montreal Protocol       https://www.pib.gov.in/PressReleasePage.aspx?PRID=1746946&reg=48&lang=2 Details on India's ratification, HFC phase-down schedule and expected climate benefits. ...Read more

27 Aug 2026

Kolkata | 27 August, 2026  India is electrifying its railway network while metro systems are adding solar power, renewable procurement and energy-efficiency measures. But as passenger numbers rise, the next challenge is deeper: making the electricity, stations and first- and last-mile connections cleaner without confusing infrastructure announcements with actual emissions cuts. SummaryIndia's railway and metro systems are undergoing a major energy transition. Indian Railways had electrified 99.6% of its broad-gauge network by July 2026, while about 1,161 MW of solar and 103 MW of wind capacity had been commissioned by June 2026. Railway electrification has also sharply reduced diesel use for traction. Delhi Metro is increasing its renewable-energy use while passenger demand continues to grow. Kolkata Metro offers another lesson through energy-efficiency improvements alongside expanding ridership. The transition therefore cannot be judged only by kilometres electrified, solar capacity installed or green-station certifications. The stronger test is whether renewable electricity is actually being used, energy consumption per passenger falls, emissions decline within a clearly defined boundary and investments deliver measurable results. Can India’s railway system go green as fast as it electrifies?  For decades, diesel locomotives were a visible part of India’s railway emissions story. Electrification has changed that equation dramatically. Indian Railways has pushed electrification at an exceptional pace. By July 2026, Indian Railways had electrified 99.6% of its broad-gauge network, with only a small portion yet to be electrified. Between 2014 and 2026, around 48,072 route kilometres were electrified, compared with roughly 21,801 kilometres during the six decades before 2014. The transition has also reduced diesel use for railway traction. Indian Railways reported that traction-related diesel consumption fell from 293 crore litres in 2015-16 to 108 crore litres in 2024 - 25.That represents a major operational shift. But electrification raises the next question: What powers the electricity? Switching from diesel to electric locomotives reduces direct emissions, but the overall climate benefit also depends on the source of the electricity used to power them. Electrification therefore removes one major source of direct emissions, but it does not automatically make the railway system renewable or zero-carbon.That makes renewable energy the next stage of the transition. Indian Railways reported that, as of June 2026, around 1,161 MW of solar capacity and 103 MW of wind capacity had been commissioned. The solar capacity includes both rooftop and land-based projects.The numbers show that the railway’s transition is moving beyond simply replacing diesel with electricity. The next challenge is to make more of that electricity cleaner - and to measure how much renewable power actually contributes to the railway’s overall energy demand and emissions reduction. THE ELECTRIC RAILWAY TEST  DIESEL TRACTION↓RAILWAY ELECTRIFICATION↓HIGHER ELECTRICITY DEMAND↓RENEWABLE POWER↓ACTUAL CLEAN ELECTRICITY USED↓LOWER EMISSIONS PER JOURNEY Electrification is the transition. Cleaning the electricity is the deeper decarbonisation test. Can railway stations become power producers instead of just power consumers?Railway stations offer a natural opportunity for solarisation. Their rooftops, parking areas and other available spaces can support solar installations, allowing electricity to be used at the station or integrated into wider railway operations. The scale of this effort has grown rapidly. In November 2025, Indian Railways reported 898 MW of commissioned solar capacity across 2,626 railway stations. Around 629 MW was intended for traction, while the remaining capacity supported non-traction requirements such as stations, workshops, service buildings and railway quarters.That figure, however, should now be treated as a milestone rather than the latest national total. By June 2026, Indian Railways reported around 1,161 MW of commissioned solar capacity.Installed capacity alone does not tell the full story. What matters is how much renewable electricity is actually generated and used. A stronger assessment would therefore ask:•    How much electricity is the solar capacity actually generating?•    How much is being used for railway operations?•    How much is supporting traction?•    When was each plant commissioned?•    What was the capital cost?•    What is its expected operating life?•    How is its performance being monitored?•    What happens to the equipment at the end of its useful life? A station covered in solar panels may look green. Renewable capacity is only part of the picture. A station that can demonstrate actual clean-energy generation, consumption and emissions avoided offers stronger evidence of meaningful decarbonisation. What happens when more passengers choose greener transport? This is where the story becomes more complicated. A public transport system can become more efficient even as its overall electricity consumption rises. Higher energy use does not necessarily mean that the system is becoming less efficient.If more people choose a metro instead of private vehicles, the system may consume more electricity overall while producing lower emissions per passenger journey. Delhi Metro provides a useful example. DMRC’s 2025 energy case study reported that solar power contributed 32% of its total energy consumption during the period assessed. The system has also used renewable electricity procurement to reduce its dependence on conventional power.Passenger demand has also grown, with Delhi Metro recording 235.8 crore passenger journeys in 2025 compared with 223.5 crore a year earlier. The figures highlight why electricity use needs to be assessed alongside passenger demand. If ridership grows faster than energy demand, the system may become more efficient. Even if total electricity consumption increases, a decline in energy use per passenger journey can indicate improved efficiency. But if both absolute electricity consumption and emissions continue to rise, a higher renewable-energy share alone does not tell the complete story. The real measure of a greener public transport system is therefore not simply how much renewable energy it uses, but whether it can move more people with a lower environmental cost per journey. ENERGY SAVINGS VS RIDERSHIP RENEWABLE SHARE ↑RIDERSHIP ↑ENERGY EFFICIENCY ↑↓CHECKTotal energy useEnergy per passengerCarbon per passengerAbsolute emissions A greener network should be measured against the people it moves, not only the infrastructure it installs. Can Kolkata Metro cut emissions by using less electricity in the first place?Kolkata Metro offers a different lesson in decarbonisation: sometimes the cleanest unit of electricity is the one the system does not need to consume.The transition does not always require a new renewable-energy plant. Improving the efficiency of existing infrastructure can also reduce energy use and emissions.Metro Railway Kolkata has been replacing its older steel third rail with a more conductive aluminium third-rail system. The railway has stated that the upgrade can reduce energy losses by 84% on the affected system, while also reducing voltage drops and improving operational efficiency. The project highlights a simple but important principle:Electricity generated from clean sources is still wasted if it is unnecessarily lost before reaching the system that needs it. That makes energy efficiency an important part of railway and metro decarbonisation. More efficient traction systems, regenerative braking, better station cooling, energy-efficient lighting and improved energy management can all complement renewable-energy procurement. Kolkata also demonstrates why ridership needs to be part of the climate discussion.After the Green Line became fully operational in August 2025, daily ridership rose from around 78,000 to 2.04 lakh.More passengers can naturally increase a metro system’s electricity demand. But that does not automatically mean its environmental performance is worsening. If those additional passengers are shifting from private cars, motorcycles or other more carbon-intensive modes, the wider transport system could still be reducing emissions. Can a Metro Be Truly Green If Passengers Still Depend on Cars to Reach It? A metro journey does not begin when a passenger enters the station.It begins at home.That makes first- and last-mile connectivity an important part of the decarbonisation story. A passenger who walks, cycles or uses an electric feeder to reach a metro station has a very different emissions profile from someone who drives a petrol or diesel vehicle to the station. A metro’s climate benefit does not depend only on the train journey. How passengers get to and from the station matters just as much. A low-carbon metro cannot be judged only by what happens on the tracks. The entire passenger journey has to be considered. That means the transition needs to connect: Homes → Feeder transport → Metro/Railway → Feeder transport → Destination Electric buses, e-rickshaws, shared mobility, cycling infrastructure and safe pedestrian routes can extend the climate benefits of mass transit beyond the station gates. This means metro corporations need to look beyond the electricity used to run their trains. The wider question is whether the transport network makes it easy for passengers to complete their entire journey through low-emission modes. The key question is:Are metro systems making it easier for people to reach and leave stations without having to fall back on high-emission private transport?A metro may run on clean electricity, but its full environmental benefit is limited if passengers still need petrol or diesel vehicles to complete the first and last mile. THE LOW-CARBON JOURNEY HOME↓🚶 WALK / CYCLEor⚡ ELECTRIC FEEDER↓🚇 METRO / RAILWAY↓🚶 WALK / CYCLEor⚡ ELECTRIC FEEDER↓DESTINATION The train can be green. The entire journey needs to move in the same direction. Does a green railway-station certificate prove that a station is sustainable? Not by itself.Green-building and green-station certifications can provide a useful framework for improving a station’s performance across areas such as energy efficiency, renewable energy, water conservation and waste management. The IGBC Green Railway Stations rating system, for example, covers several of these areas and can help guide stations towards more sustainable design and operations.But certification and actual environmental performance are not the same thing. A stronger evidence test should ask:What was the baseline? What did the reporting boundary include? Which measures were actually commissioned? How much energy is being saved? How much water is being conserved or reused? What was budgeted, and how much was actually spent? Are the claimed savings still being measured after implementation? These questions matter because a green rating can demonstrate that specific sustainability measures have been incorporated into a project. It does not automatically prove that the station is delivering the same level of long-term carbon reduction in its day-to-day operations. Ultimately, a certificate can show what a station was designed or assessed to achieve. Actual performance data shows what it is achieving in practice. Beyond Electrification: How Green Is the Railway? THE GREEN TRANSIT SCORECARD EvidenceWhat should be measuredElectrificationRoute kilometres + commissioning dateSolarInstalled MW + actual generationWindInstalled MW + actual generationTractionRenewable electricity actually usedStationsSolar coverage + electricity consumptionEfficiencyEnergy saved + energy intensityRidershipPassenger journeys + passenger-kmEmissionsAbsolute + intensity emissionsFirst/last mileEV and public-transport connectivityCertificationBaseline + reporting boundary + performanceInvestmentBudget/capex + money actually spentOffsetsQuantity, type and relianceLifecycleConstruction, equipment and end-of-life impacts This is where corporate and government reporting needs to become much more transparent. A company supplying renewable-energy infrastructure should clearly distinguish between capacity that has been announced, installed and actually commissioned. A railway authority should separate electricity generated from electricity actually consumed. A metro corporation should demonstrate whether renewable-energy procurement is translating into measurable changes in its emissions profile. Similarly, green-station certification should be treated as one part of the sustainability assessment, not a substitute for measuring the station’s wider emissions and resource use. The distinction may sound technical, but it determines whether sustainability claims reflect what is actually happening on the ground. Can the world’s largest passenger railway network decarbonise without compromising access? There is no single technology that can answer that question. Electrification is essential, but it is only the first layer of the transition. Solar and wind power can reduce the carbon intensity of railway electricity. More efficient traction systems can reduce energy losses. Greener stations can lower energy and water demand. Metro expansion can shift passengers away from private vehicles. Electric buses and feeders can connect neighbourhoods to mass transit while keeping the wider journey cleaner. Together, these measures can move the railway and public-transport system towards lower emissions without making access to mobility more difficult. But every layer creates a new measurement challenge.The sector needs to distinguish between announced and commissioned projects, installed capacity and actual generation, renewable-energy procurement and actual renewable-energy consumption, and energy savings and measurable emissions reductions. It also needs to account for the lifecycle footprint of new tracks, stations, trains, solar equipment and other infrastructure, rather than measuring only the emissions produced during day-to-day operations. The goal is not simply to build a railway that uses more clean technology. It is to build a transport system that can demonstrate, with evidence, that it is moving more people while reducing the environmental cost of that mobility. THE REAL DECARBONISATION TEST  ELECTRIFY↓POWER WITH RENEWABLES↓REDUCE ENERGY LOSSES↓GROW RIDERSHIP↓CONNECT FIRST & LAST MILE↓MEASURE EMISSIONS PER PASSENGER↓VERIFY SPENDING & PERFORMANCE  India’s Railways Are Going Electric. But Are They Truly Low-Carbon? The evidence points to a major transition - but not a finished one.Indian Railways has reached 99.6% broad-gauge electrification, while its latest reported renewable-energy capacity stood at 1,161 MW of solar and 103 MW of wind commissioned by June 2026. Traction-related diesel consumption has also fallen substantially over the past decade. These are significant milestones. But electrification is not the finish line. It is the foundation for the next stage of decarbonisation. The harder task now is to clean the electricity powering the network, reduce energy losses, expand public-transport use and make the entire passenger journey lower-carbon - from the first mile to the last. For Indian Railways and the country’s expanding metro systems, the strongest sustainability claim will therefore not simply be:“We electrified the railway.”It will be:“We can show how much cleaner each journey has become - where the electricity came from, how much energy and carbon were actually saved, what was spent and what changed on the ground.” That means moving beyond headline numbers and proving the difference between infrastructure installed and performance achieved. Because a railway does not become truly green simply because its locomotives run on electricity. Electrifying the railway is a major step. But it is not the finish line. The transition becomes truly green when the electricity gets cleaner, energy losses fall, more people choose mass transit, and emissions per journey show a measurable decline.That is what India’s green rail transition must ultimately prove: not simply that more tracks are electrified, but that every step is making the country’s mobility cleaner and lower-carbon.  Sources: Indian Railways / Ministry of Railways — Railway Electrification & Renewable Energy, July 2026Supports the latest 99.6% broad-gauge electrification, the 1,161 MW solar + 103 MW wind commissioned by June 2026, and the fall in traction diesel consumption from 293 crore litres in 2015-16 to 108 crore litres in 2024-25. Ministry of Railways — Railway Electrification & Renewable Energy Indian Green Building Council — Green Railway Stations Rating SystemSupports the sections on green-station certification, energy and water savings, renewable energy, waste management and first-/last-mile connectivity. It also explains the performance-improvement study and third-party assessment process. IGBC Green Railway Stations Rating System Indian Green Building Council — Green High Speed Rail Rating SystemUseful for the broader low-carbon rail infrastructure, lifecycle/site boundary and first-/last-mile connectivity discussion. IGBC Green High Speed Rail Rating System Indian Railways — Renewable Energy / Solarisation milestonesUse this for the earlier 898 MW solar capacity across 2,626 stations milestone that appears in the article as historical context. For the latest figure, use the July 2026 Ministry of Railways release above. Delhi Metro Rail Corporation — Sustainability / Energy documentationThis is the source to retain for the Delhi Metro solar contribution, renewable procurement, energy efficiency and ridership portions. The official DMRC site is also the appropriate primary source for its operational and sustainability documentation. Delhi Metro Rail Corporation ...Read more

24 Aug 2026

SPECIAL FEATURE | GREEN RAILWAYS, METRO SOLARISATION & LOW-CARBON PUBLIC TRANSIT India has nearly electrified its railway spine. Now comes the harder revolution: cleaning every electron, solarising stations, firming metro power, electrifying the last mile - and proving the carbon savings. BLURBIndia has almost finished the great engineering task of electrifying its broad-gauge railway. The harder transition starts now: making the electricity genuinely low-carbon, turning station roofs and railway land into productive energy assets, using storage and regenerative braking intelligently, and ensuring that the first and last kilometre do not push passengers back into fossil-fuelled vehicles. The test of a green railway is no longer how many megawatts it announces, but how much verified low-carbon mobility it delivers - per passenger, per tonne and across the full life cycle. IN BRIEFIndian Railways reached 99.6% broad-gauge electrification by March 2026 while carrying about 741 crore passengers in FY2025-26. India also crossed 1,155 km of operational metro rail across 26 cities, with daily metro ridership above 1.15 crore. This scale makes rail one of India's most important climate assets, but electrification alone does not eliminate emissions: grid electricity, construction materials, storage, maintenance, last-mile access and accounting methods all matter. The next phase must combine distributed solar, firm renewable procurement, batteries, regenerative braking, low-carbon station design, electric feeder networks and transparent carbon ledgers. Delhi, Kolkata, Kochi, Howrah, Germany, the Netherlands and Santiago offer practical lessons. The central policy message is simple: measure mobility outcomes, not installed capacity alone. HASHTAGS  #GreenRailways #SolarMetros #LowCarbonTransit #IndianRailways #CleanMobility #PublicTransport #EnergyTransition #NetZeroMobility #EVFeeders #SustainableCities DATA NOTE  Facts and project status rechecked to 18 August 2026. Operator estimates and corporate disclosures are identified as such; tendered/awarded capacity is not treated as commissioned capacity. 99.6%Broad-gauge network electrified by Mar 2026741 crorePassenger journeys in FY2025-26>1,260 MWSolar + wind commissioned by mid-20261,155+ kmMetro operational across 26 cities by Mar 2026 Electrification Was the Great First Act At dawn, before the first commuter boards, the railway is already drawing electricity for signals, lifts, escalators, workshops, depots, station lighting, ventilation and traction substations. By March 2026, 99.6% of Indian Railways' broad-gauge network was electrified. The system carried about 741 crore passenger journeys in FY2025-26 and operates roughly 25,000 trains a day. Few infrastructure systems on earth operate at this scale. The speed of the conversion is striking. The Ministry of Railways says about 48,072 route kilometres were electrified between 2014 and 2026, compared with 21,801 route kilometres before 2014. Diesel used for traction fell from 293 crore litres in 2015-16 to 108 crore litres in 2024-25. Between FY2020-21 and FY2024-25, actual expenditure reported on railway electrification projects was Rs 29,826 crore; the traction-energy bill itself was Rs 32,378 crore in FY2024-25. That achievement delivers three structural benefits. Electric traction removes locomotive exhaust from dense station areas and corridors; it improves the efficiency and performance potential of the fleet; and, most importantly, it makes the energy source substitutable. A diesel locomotive remains tied to a liquid fuel. An electric locomotive can become progressively cleaner as its power supply shifts from fossil-heavy grid electricity to solar, wind, hydro, storage-backed renewable contracts and other low-carbon sources. But this is where the celebratory language must become more exact. Electrification eliminates a large part of Scope 1 traction emissions; it does not automatically eliminate Scope 2 emissions from purchased electricity, and it says nothing about the embodied carbon in steel, concrete, rolling stock, batteries, substations or construction. The government's own rail-versus-road comparison points to rail's major efficiency advantage - around 89% lower CO2 in the cited comparison - but the climate prize is fully captured only when the electricity itself gets cleaner and more journeys shift from higher-carbon modes to rail. Megawatts Are Not Megawatt-Hours Indian Railways reported roughly 1,161 MW of commissioned solar capacity and 103 MW of wind by June 2026. The distributed footprint was already broad: by November 2025, 2,626 railway stations were using solar power, and 898 MW of solar had been commissioned, with 629 MW then being used for traction and 269 MW for non-traction loads. That is real progress. Yet the key word is commissioned. Over the years, railway renewable announcements have mixed targets, tenders, awarded capacity, signed power-purchase agreements and operating plants. They are not the same thing. A 500 MW award does not reduce one tonne of CO2 until the project is built, connected, dispatched and contractually attributed to railway consumption. The same discipline is needed for the railway's 2030 ambition. Government planning has linked the net-zero goal to projected electrical demand of roughly 8,200 MW by 2029-30 and a renewable-installation requirement of about 30 GW. That 30 GW is a target for a future portfolio, not today's operating renewable fleet. Reporting should therefore lead with renewable megawatt-hours delivered to railway loads, not only megawatts of nameplate capacity. The engineering possibilities are expanding. In 2020, the 1.7 MW Bina pilot in Madhya Pradesh demonstrated direct connectivity of solar generation to the 25 kV traction system. The deeper opportunity is to combine distributed station and depot solar with utility-scale renewable power, storage and smart dispatch. Solar roofs are excellent for daytime auxiliary loads, but trains run through the night and peak traction demand does not politely follow the sun. Station roofs and railway land are also not frictionless assets. Old roofs may be structurally constrained; heritage stations may limit visual interventions; dust, heat and bird fouling can cut output; monsoons raise waterproofing risks; and cyclone-prone eastern India requires more demanding wind-load design. Every rooftop programme should therefore start with a station-level energy and structural audit and end with a performance contract covering generation guarantees, degradation, inverter replacement, fire access, operations and maintenance, surplus power, insurance, and end-of-life module recycling. THE REPORTING RULECapacity is not generation. Annual renewable generation is not round-the-clock clean supply. A PPA is not a commissioned plant. A certificate is not a physical electron. Every claim should identify status, actual MWh delivered and the accounting boundary. Delhi: From Solar Panels to a Power Portfolio Delhi Metro shows why the next stage is a portfolio problem rather than a rooftop problem. DMRC's 2023-24 annual report listed about 50 MWp of rooftop solar capacity and procurement of 349 million units of solar electricity from the Rewa project during the year. Renewable sources accounted for about one-third of its energy requirement. The important innovation is not only the panel count; it is the ability of a large, creditworthy transport utility to aggregate demand and contract renewable supply at scale. DMRC has since moved toward storage-backed procurement. In October 2025 it issued a central e-procurement tender for inter-state captive renewable supply built around solar photovoltaic generation with co-located battery energy storage. Industry reporting on the tender described a requirement of about 500 million units a year, with roughly 170 MW of solar and 680 MWh of battery storage. The tender's 455-day supply period is a reminder that project status matters: tendered capacity must not be reported as commissioned capacity. Storage changes the operating logic. Solar generation peaks during the day, while metro demand extends into the evening. Batteries can firm renewable supply, shave demand peaks, improve resilience and create a place to capture electricity that might otherwise be curtailed. Regenerative braking adds another layer: when a train brakes, part of its kinetic energy can be returned to the traction system and used by other accelerating trains or, where the architecture allows, stored. The metric that should dominate future metro reporting is energy and carbon per passenger-kilometre. Delhi Metro recorded 2,358.03 million passenger journeys in calendar 2025, averaging 64.6 lakh daily. If ridership rises, total electricity use can rise even while efficiency improves. That is not a climate failure if the network carries far more mobility and replaces car, taxi or motorcycle trips. A metro that cuts electricity by losing passengers is not a sustainability success. Kolkata: Solarise - and Audit the Claim Kolkata Metro illustrates both the opportunity and the accounting challenge. On 1 July 2026, Metro Railway commissioned a 500 kWp rooftop solar plant at Jessore Road station. The operator expects average generation of about 1,800 units a day and annual electricity savings of roughly Rs 50 lakh, with cloud-based monitoring of plant performance. It also says awarded and planned projects could eventually take its solar portfolio toward 34.3 MWp - a forward pipeline that should be tracked separately from operating capacity. The Jessore Road case is valuable because it is a modest, measurable asset serving station loads rather than a distant headline target. Kolkata is also moving into storage. On 25 February 2026, Metro Railway inaugurated a 4 MW/6.4 MWh lithium-iron-phosphate battery energy storage system at Central station on the Blue Line. Its immediate function is resilience: during a major grid failure, it can supply emergency traction to move a stranded train toward a station and support tunnel ventilation. Over time, storage at traction substations can also become part of a wider peak-management and renewable-balancing architecture. But Kolkata offers a warning about climate arithmetic. An official October 2025 release reported 4.556 MWp of solar capacity producing about 57 lakh units annually, while also claiming a reduction of 49 lakh tonnes of carbon footprint each year. Taken literally, those numbers imply roughly 860 kilograms of CO2 avoided for every kilowatt-hour generated - an order-of-magnitude impossibility for electricity accounting. The correct response is not to dismiss the solar effort. It is to correct the emissions claim and institutionalise better reporting. Every railway zone and metro corporation should use a common CEA-aligned methodology, disclose the baseline year, the grid-emission factor used, the reporting boundary, and the treatment of physical PPAs, renewable energy certificates and offsets. The difference between installed and delivered, and between a promotional estimate and an audited carbon result, is where the credibility of green infrastructure will now be won. FACT-CHECK: WHY THE MATH MATTERSMetro Railway's October 2025 release paired 57 lakh solar units a year with a claimed 49 lakh tonnes of annual carbon reduction. Taken literally, that equals roughly 860 kg CO2 avoided per kWh - plainly irreconcilable with power-sector carbon accounting. The solar capacity is real; the emissions figure needs correction or clarification. The First and Last Kilometre Can Cancel the Carbon Win A railway station is an interchange, not the beginning or end of a journey. If a passenger must take a petrol motorcycle, a diesel auto or a private car to reach a metro, the low-carbon advantage of the main line is diluted. The climate boundary of public transport must therefore extend from doorstep to destination: safe walking, cycling, e-rickshaws, electric autos, feeder buses, shared mobility, universal access and coordinated interchange design all belong inside the decarbonisation plan. WRI India's Station Access and Mobility Program has treated this as an implementation problem rather than an aspiration. WRI reports more than 50,000 last-mile trips facilitated and over 240,000 passenger minutes saved through connectivity interventions that have included electric autorickshaws and other station-access solutions. CEEW's work on India's bus transition similarly argues for using electric buses in metro-feeder services and building the charging, contracting and financing ecosystem that makes service reliable. CEEW researcher Anannya Jha puts the priority plainly: 'Electric buses will be central to delivering clean, affordable, and inclusive mobility.' Kochi offers a useful systems example. Its rail metro is complemented by the Water Metro, a network of electric-hybrid boats that connects island communities and is designed to integrate with metro rail, buses and cycling. The lesson is not that every city needs ferries; it is that the main trunk system, its feeders and the ticketing or information layer should be planned as one mobility service. Santiago provides the Global South scale lesson. By early 2026, its Red Movilidad bus system was on course to reach about 4,400 electric buses, around 68% of the fleet, supported by large charging depots and a procurement model that separated fleet and service functions. Indian cities should treat e-buses as the capillaries of metro systems, not as a parallel EV scheme. Every new metro corridor should open with an electric-feeder plan, charging-capacity assessment, frequency obligation and a map of underserved neighbourhoods, schools, markets, hospitals and employment clusters. A Platinum Plaque Is Not a Carbon Ledger The Indian Green Building Council and Indian Railways have already created the Green Railway Stations Rating System, covering energy, water, waste, site planning, passenger experience and environmental performance. Howrah station is a strong eastern India example. Eastern Railway reported that Howrah moved from Gold to Platinum in January 2024 with a score of 83, after initiatives including energy and water audits, rainwater harvesting, waste segregation, air-quality measures, SCADA and extensive rooftop solar coverage. Certification is useful because a station is simultaneously a building, a workplace, a commercial precinct, a mobility hub and a neighbourhood gateway. A genuinely green station should combine efficient equipment and solar generation with water conservation, waste recovery, shade and heat mitigation, universal accessibility, safe walking and cycling access, low-emission feeders, clean indoor air and resilience to heatwaves, floods and extreme rainfall. The next generation of certification should, however, move from design intent to post-occupancy performance. A station should not remain 'green' because panels, meters or rainwater tanks were installed five years ago. Annual recertification data should include electricity per passenger, renewable generation and consumption, water per passenger, waste diverted from landfill, accessibility performance, Scope 1 and Scope 2 emissions, climate-risk readiness, capital and operating expenditure, equipment uptime and savings against a published baseline. Concrete, Steel, Batteries: Count the Hidden Carbon The most misleading phrase in urban rail is 'zero-emission metro'. Electric trains may have no tailpipe, but tunnels require large volumes of concrete; viaducts require cement and steel; stations use glass, aluminium, HVAC and electrical systems; rolling stock carries embodied emissions; construction machines burn fuel; and solar modules and batteries eventually require recovery and recycling. TERI researchers comparing a Delhi Metro case with an Ahmedabad bus rapid transit case showed why lifecycle boundaries matter. Their context-specific study found that while metro rail was highly energy-efficient, the addition of infrastructure and other lifecycle emissions could change the CO2-per-passenger-kilometre comparison. The lesson is not 'do not build metros'. It is: build them in corridors with sufficient long-term ridership, optimise structures, and count the carbon embedded in what is built. Metro detailed project reports should therefore include an embodied-carbon budget alongside the financial budget. Procurement can reward lower-carbon cement and steel, recycled aggregates, leaner structural design, electric construction equipment where feasible, Environmental Product Declarations and end-of-life responsibility. Battery and solar contracts should specify chemistry, expected life, performance degradation, fire safety, refurbishment and recycling pathways. Hydrogen belongs in this technology hierarchy too - but as a niche solution, not a universal replacement for wires. On 17 July 2026, India flagged off its first hydrogen-powered train on the Jind-Sonipat section. The current configuration uses two 1.2 MW power cars, giving 2.4 MW total propulsion power, supported by batteries; a dedicated storage facility at Jind holds about 3,000 kg of hydrogen. The train has no tailpipe CO2, but its lifecycle climate value still depends on how the hydrogen is produced. Where overhead electrification is technically or aesthetically difficult - heritage or isolated routes, for example - green hydrogen or battery-electric traction may be useful. On dense main lines, direct electrification remains the efficiency benchmark. What the World Teaches: Match Energy, Measure Mobility Germany's Deutsche Bahn offers a mature procurement lesson. DB reported that 69.8% of its traction current mix was renewable in 2024 and is pursuing 80% by 2030 and 100% by 2038. Its strategy is broader than rooftop solar: it uses long-term procurement across renewable technologies and works within a railway-specific electricity architecture. For India, the lesson is diversification - solar for daytime, wind and other sources with different production profiles, storage and firming for night operations, and contracts that clearly identify what is delivered and when. The Netherlands adds a more subtle accounting lesson. NS reported 16.5 billion passenger-kilometres in 2025, up from 16.1 billion, while energy intensity improved from 69.6 to 68.4 Wh per passenger-kilometre. Crucially, its climate reporting distinguishes market-based electricity emissions from location-based emissions and includes material Scope 3 categories, including passenger journeys before and after the train. Renewable Guarantees of Origin are disclosed as accounting instruments rather than confused with the physical hourly grid mix. This is exactly the transparency India needs. A metro buying certificates should not imply that every train is physically powered by zero-carbon electrons at every hour. Onsite generation, physical PPAs, open-access renewable supply, grid electricity, storage, certificates and offsets should be disclosed separately. Avoided emissions should also be distinguished from an organisation's own emissions inventory. The broader Global South lesson is to leapfrog selectively. Santiago demonstrates that large electric feeder fleets and charging depots can be built in a middle-income urban system. Kochi demonstrates multimodal integration across rail and water. Modelling work in South Asian cities, including studies of rooftop solar opportunities for Dhaka MRT, can help size investments - but modelled avoidance must always be labelled as a scenario until meters and operating data exist. Corporate India: From Capability to Contracted Carbon The corporate ecosystem matters, but the evidence test must be project-specific. Renewable developers, EPC companies, battery manufacturers and fuel suppliers can all support rail decarbonisation. Their corporate portfolio numbers, however, do not become railway carbon savings by association. A transit claim should be tied to a named asset, commissioning status, contracted delivery, measured MWh or charging uptime, lifecycle boundary and capital actually deployed. EntityEvidence statusWhat the evidence supportsNTPC / NTPC GreenDirect rail linkNTPC Renewable Energy won a 500 MW RE-RTC award from REMCL in 2023; report commissioning date and delivered MWh before claiming reduction.ReNewDirect rail linkSigned a 200 MW RTC PPA with REMCL in Jan 2025; underlying portfolio was estimated at ~600 MW. PPA status is not operating status.L&TMetro operator + EPCL&T Metro Rail Hyderabad lists 9.35 MWp solar across depots and 32 station roofs, meeting about 12% of its electricity requirement; L&T also brings rail EPC capability.Tata PowerAdjacent capabilityLarge renewables and charging platform; 1,200+ e-bus charging points reported in 2026. Transit benefit needs named contract, uptime and MWh.Adani GreenAdjacent capabilityUtility-scale renewables and large BESS capability, including multi-GWh storage at Khavda. Do not infer railway savings without a rail contract.Reliance New EnergyManufacturing capabilityBuilding integrated solar and battery manufacturing. Rail relevance is future supply-chain potential unless a specific transit asset is contracted.IndianOilLast-mile / fuels capability14,000+ EV charging stations reported by Aug 2026. Useful feeder ecosystem potential; project emissions and charging delivery must be separated from group-wide claims.GAILSolar + storage capabilityApproved 700 MW of solar projects with battery storage in 2026. These are not rail projects unless contracted and delivered to transit loads. Two direct railway procurement examples show the importance of status language. NTPC Renewable Energy received a Letter of Acceptance in 2023 for 500 MW of round-the-clock renewable capacity for REMCL, combining solar and wind under a proposed 25-year arrangement. ReNew disclosed in January 2025 that it had signed a 200 MW round-the-clock PPA with REMCL, backed by an estimated 600 MW of underlying renewable capacity. These are important contracting milestones, but the emissions ledger should move only as projects commission and electricity is delivered. The same rule applies to supplier capability. Tata Power's more than 1,200 e-bus charging points, Adani Green's large BESS deployment at Khavda, Reliance's battery-manufacturing build-out, IndianOil's more than 14,000 EV charging stations and GAIL's new solar-plus-storage approvals demonstrate potentially relevant industrial capacity. None should be counted as a rail or metro emissions reduction unless a specific transit contract can show commissioning, delivery and a defensible baseline. For fossil-fuel incumbents such as IndianOil and GAIL, project-level transparency is even more important. Green hydrogen, charging, biofuels or storage can be useful transition businesses, but their benefits should not be allowed to obscure the emissions profile of the wider corporation. Public transport procurement should buy outcomes, not corporate narratives. Rules Exist. The Missing Piece Is a Carbon Protocol India does not need to invent the enabling architecture from scratch. The Ministry of Power's Green Energy Open Access Rules reduced the eligibility threshold to 100 kW, widening the pool of consumers that can contract renewable electricity. CERC provides the electricity-market and certificate framework; CEA maintains the country's CO2 baseline database; MNRE sets renewable and storage policy; SECI structures competitive procurement; BEE can strengthen efficiency benchmarks and audits; and the Ministry of Railways, RITES/REMCL and metro corporations can aggregate demand and execute contracts. What is missing is a common Rail and Metro Carbon Protocol. It should be jointly designed by the Ministry of Railways, MoHUA, Ministry of Power, MNRE, CEA, CERC, BEE, SECI, RITES/REMCL and state metro corporations. It should define the reporting boundary and force every major system to publish an annual dashboard using the same vocabulary. At minimum, the dashboard should show total traction and non-traction electricity; onsite renewable generation; renewable MWh physically procured; storage charge/discharge and availability; Scope 1 and both location-based and market-based Scope 2 emissions; material Scope 3 emissions; passenger journeys and passenger-kilometres; tonne-kilometres for freight; kWh and gCO2e per unit of mobility; modal-shift estimates; and capital allocated, contracted and actually spent. This is also where independent scrutiny by CEEW, TERI, WRI India, CSE and IEEFA South Asia is valuable. CSE's urban-mobility warning remains concise: 'Cities will have to reduce health risk and climate risk together.' IEEFA's storage work makes the system point equally clearly: 'Energy storage is integral to renewable integration and grid resilience.' The transition is not only an engineering programme; it is an accountability programme. THE 10-POINT GREEN-RAIL EVIDENCE TEST• Name the asset, location, technology and lifecycle boundary.• State status and date: announced, tendered, awarded, PPA signed, under construction, commissioned or operating.• Report nameplate MW/MWp and actual MWh delivered.• Show the power source by time period, grid imports, storage and curtailment where material.• Publish Scope 1, location-based and market-based Scope 2, plus material Scope 3.• Separate physical renewable supply, RECs/GoOs and carbon offsets.• Disclose the baseline year and denominator: passenger-km or tonne-km.• Publish both absolute emissions and intensity results.• Distinguish capex approved, committed and actually spent; include O&M and uptime.• Use independent assurance and a public correction protocol for material errors. 2035: Build a Clean-Mobility Operating System Imagine the railway of 2035 not as a set of trains, but as a national mobility-energy operating system. Station roofs, depots, parking canopies and suitable railway land produce solar electricity. Wind and solar farms hundreds of kilometres away supply traction through long-term contracts. Batteries at selected substations absorb cheap midday energy, smooth acceleration peaks and support emergency operation. Pumped hydro and other firming resources cover longer-duration needs. Regenerative braking feeds usable energy back into the system. Artificial intelligence forecasts passenger loads and adjusts train frequency, cooling and station demand. Digital twins predict component failures and optimise maintenance. Feeder buses arrive according to train schedules. E-autos are geofenced into organised interchange areas. Walking routes are shaded and barrier-free. Bicycles and shared mobility sit inside the same journey-planning layer, while interoperable payment through NCMC and future mobility-as-a-service platforms makes transfers less punitive. The rural opportunity is just as important. Railway stations in district towns can become clean-mobility hubs for electric buses, e-rickshaws and shared vehicles linking villages to regional rail. Solar canopies can provide daytime charging; storage can reinforce weak local grids; station redevelopment can combine logistics, public services and resilient cooling. Decarbonisation then becomes not an elite metropolitan project, but a public-service upgrade across the country. The investment rule should be 'efficiency first, renewable second, storage where valuable, offsets last'. Reduce waste through LEDs, efficient pumps, variable-speed drives, optimised ventilation and cooling, timetable management and regenerative braking. Then replace remaining electricity with additional renewable supply. Use storage where it reduces peak charges, improves resilience or increases renewable utilisation. Reserve offsets for residual emissions that cannot yet be eliminated, and disclose them separately. The final accountability shift is from infrastructure completion to mobility performance. Each new project should publish a commissioning timetable and then a post-commissioning record: actual energy generation, uptime, MWh delivered, tariff, savings, carbon factor, passenger intensity, first/last-mile access and lifecycle impacts. If a project misses its stated performance, the annual report should say why and what will be corrected. The Destination Is Mobility, Not Megawatts India has almost completed one of the largest railway electrification transformations in history. The achievement is historic, but it was the easier revolution. The next one is more difficult because it cuts across the power system, station architecture, rolling stock, city streets, procurement rules, data standards and passenger behaviour. The winning formula is now visible: electrify the network; decarbonise the electricity; cut energy intensity; build storage and flexibility where they add value; design electric first- and last-mile services into the network; certify stations for measured performance; reduce embodied carbon; and report the lifecycle honestly. Rail can carry more people and freight while reducing carbon intensity - but only if India measures both absolute emissions and emissions per unit of mobility. The greenest train is not the one with the most solar panels in the photograph. It is the one embedded in a system where clean power, efficient operations, resilient stations, transparent accounting and low-emission access make the entire journey better. If India can achieve that at its extraordinary scale, it will do more than decarbonise a railway. It will build one of the world's most consequential and affordable laboratories for low-carbon mass mobility - and give the Global South a model worth adapting.   SOURCEBOOK | VERIFIED PRIMARY AND AUTHORITATIVE REFERENCES 1. Press Information Bureau, Ministry of Railways. The Ever-Evolving Journey of Railways. 15 Apr 2026. Source link 2. Press Information Bureau, Ministry of Railways. India Emerges as Global Leader in Railway Electrification.... 22 Jul 2026. Source link 3. Press Information Bureau, Ministry of Railways. 2,626 Solar-Powered Railway Stations Supporting Cleaner Operations. 16 Dec 2025. Source link 4. Press Information Bureau. 25 States Achieve 100% Railway Electrification. 11 Feb 2026. Source link 5. Press Information Bureau, Ministry of Railways. Indian Railways set to meet all its energy consumption needs... (Bina direct traction solar). 27 Aug 2020. Source link 6. Press Information Bureau, Ministry of Railways. Indian Railways to become Net Zero Carbon Emitter by 2030. 15 Mar 2023. Source link 7. Press Information Bureau. The Story of India's Hydrogen Train. 25 Jul 2026. Source link 8. Press Information Bureau. Ease of Living: India's Journey of Inclusive Progress. 15 Jun 2026. Source link 9. Delhi Metro Rail Corporation. Annual Report 2023-24. 2024. Source link 10. Delhi Metro Rail Corporation. Delhi Metro - the lifeline of Delhi-NCR.... 15 Mar 2026. Source link 11. Government of India eProcurement System / DMRC. RfS ORE/CGP/01: ISTS captive solar PV with co-located BESS. 8 Oct 2025. Source link 12. Mercom India. Delhi Metro Invites Bids to Procure 170 MW Solar, 680 MWh BESS. 10 Oct 2025. Source link 13. Metro Railway Kolkata. 500 KWP Solar Power Plant at Jessore Road. 3 Jul 2026. Source link 14. Metro Railway Kolkata. BESS inaugurated in Blue Line. 25 Feb 2026. Source link 15. Metro Railway Kolkata. Metro generating solar power to reduce carbon footprints. 14 Oct 2025. Source link 16. Eastern Railway. Coveted IGBC Platinum Rating Awarded to Howrah Station. 4 Jan 2024. Source link 17. World Resources Institute India. Unlocking Connectivity to Mass Transit in India. accessed 18 Aug 2026. Source link 18. Council on Energy, Environment and Water. How can India's Bus Market Scale up Sustainable Public Transport?. 25 Sep 2025. Source link 19. The Energy and Resources Institute. Carbon footprint of urban public transport systems in Indian cities. research paper. Source link 20. Centre for Science and Environment. Media briefing on urban mobility and climate change. 17 Feb 2017. Source link 21. IEEFA / JMK Research. The standalone energy storage market in India. 28 Apr 2025. Source link 22. Deutsche Bahn. Integrated Report 2025 - share of renewable energies in DB traction current mix. 2026. Source link 23. Deutsche Bahn. How Deutsche Bahn uses solar energy. accessed 18 Aug 2026. Source link 24. NS (Nederlandse Spoorwegen). Annual Report 2025 - Sustainability / Climate and Energy. 2026. Source link 25. Institute for Transportation and Development Policy. 2026 Sustainable Transport Award case material: Santiago and Kochi. 13 Jan 2026. Source link 26. NTPC. NTPC wins 500 MW RE-RTC capacity for Indian Railways. 28 Apr 2023. Source link 27. ReNew. 200 MW RTC PPA with REMCL. 9 Jan 2025. Source link 28. L&T Metro Rail Hyderabad. Green Metro - Eco-Friendly Transit. accessed 18 Aug 2026. Source link 29. Tata Power. Q1 FY27 results / charging network update. 27 Jul 2026. Source link 30. Adani Green Energy. Commissioning of large single-location BESS at Khavda. 26 May 2026. Source link 31. Reliance Industries. Q1 FY27 Analyst Presentation - New Energy. 17 Jul 2026. Source link 32. IndianOil. About IndianOil - EV charging network. updated 13 Aug 2026. Source link 33. GAIL (India) Limited. Approval of 700 MW solar projects with battery storage. 14 Apr 2026. Source link 34. Ministry of Power / PIB. Green Energy Open Access Rules, 2022. 2022. Source link 35. Central Electricity Authority. CDM CO2 Baseline Database - Version 21.0. accessed 18 Aug 2026. Source link 36. Ministry of New and Renewable Energy. Schemes, guidelines and Energy Storage Systems. accessed 18 Aug 2026. Source link ...Read more

18 Aug 2026

Kolkata| 18 August, 2026  As renewable energy, electric mobility and sustainable agriculture create new livelihood opportunities, the real test for CSR is whether women gain lasting access to skills, decent wages, finance and leadership - not just training certificates. SummaryIndia’s green transition is opening opportunities across solar energy, electric mobility, sustainable agriculture and other emerging sectors. Yet women remain underrepresented in many technical clean-energy jobs. A 2026 CEEW-NRDC analysis found that women account for only 11% of the workforce in India’s solar and wind deployment and manufacturing sectors, while more than half of the women working in these sectors are in non-technical roles. At the same time, India’s clean-energy ambitions could create more than 44 lakh full-time-equivalent jobs. The opportunity is therefore significant, but access remains uneven. CSR can help women enter technical occupations and build green enterprises by combining training with employment, finance, market access, safety and social protection. Its success, however, should be measured by wages, retention, benefits and income growth rather than the number of women trained alone. Can Women Become a Key Workforce in India’s Green Transition?India’s green economy is opening up job opportunities in areas that were once seen as highly technical or largely male-dominated. Solar installation and maintenance, electric-vehicle servicing, battery management, climate-resilient agriculture, waste management and energy-efficient construction are creating new career possibilities for women, including jobs with potential for long-term income and growth. But women are still significantly underrepresented in these roles. The latest CEEW-NRDC analysis shows that women account for only 11% of the workforce across solar and wind deployment and manufacturing. Their representation is highest in rooftop solar, at 15%, while wind manufacturing has only around 6% women workers. More than half of the women employed across the clean-energy sectors studied are still working in non-technical roles such as administration, accounting and human resources. This raises an important question for companies supporting green CSR and skilling programmes: Are they actually preparing women for technical careers, or are they mainly directing them towards support roles? India’s clean-energy targets could generate more than 44 lakh full-time-equivalent jobs. If women remain largely excluded from technical positions, a significant share of this employment opportunity could remain out of reach for them. Where Is the Missing Link?India already has programmes aimed at building a skilled renewable-energy workforce. The government’s Suryamitra programme, for instance, trains solar photovoltaic technicians in installation, operation and maintenance, with more than 51,000 Suryamitras trained by the end of 2022. But completing a training programme does not mean automatically securing a job. A woman may earn a technical certificate and still struggle to find employment because of limited transport to project sites, lack of equipment, workplace barriers or the challenge of balancing paid work with unpaid care responsibilities. This is where CSR programmes need to rethink how they measure success. Reporting that 1,000 women completed a training course shows the reach of a programme, but it does not show whether the training improved their livelihoods or not. The more meaningful questions are: How many women found jobs? How much did they earn? How many remained employed after six or 12 months? How many moved into technical roles? How many received social-security benefits? And how many were able to progress in their careers? The focus therefore needs to shift from how many women were trained to how many women are earning, staying employed and moving forward in the green economy.Can Women Turn Green Skills into Real Jobs? Women are already entering technical and clean-energy roles, showing that green-skills training can create real employment opportunities when it is linked to actual jobs and local demand. Government programmes have documented women receiving training in solar installation and maintenance, while other clean-energy initiatives are helping women from communities whose traditional livelihoods are changing to access new opportunities in the renewable-energy sector.The key lesson is clear: training creates greater impact when it is designed around the skills and jobs that are actually in demand in the local economy. For example, A CSR programme in a region experiencing rapid growth in solar installations could equip women with skills in installation, maintenance and after-sales services, helping them access emerging employment opportunities in the sector. Near an electric-mobility hub, training could focus on EV diagnostics, battery maintenance and charging infrastructure. The same approach can work in agriculture. Women farmers could be trained in climate-resilient farming, efficient irrigation, solar-powered agricultural equipment, soil management, livestock services and value-chain activities. The goal should not be to simply add more people to the list of training certificate holders. Instead, it should be to create sustainable local green livelihoods that provide a steady source of income and remain viable even after CSR funding ends. Can Green Skills Help Women Build Their Own Businesses? A job is not the only way women can participate in the green economy. For many, entrepreneurship could offer a more flexible and sustainable route to earning a livelihood. A woman trained in solar maintenance could become a local service provider. A group of women could run a farm-equipment service centre. An EV-trained technician could start a small repair business. A farmer could adopt climate-smart practices and better equipment to improve productivity and access higher-value markets. But training alone is not enough to turn these skills into viable businesses. Women also need working capital, equipment, access to credit, digital payment systems and reliable market connections. India already has a strong institutional network that can support this transition. By February 2026, DAY-NRLM had mobilised more than 10.05 crore rural women into over 90.90 lakh self-help groups, while cumulative bank credit to women’s SHGs had crossed ₹11.10 lakh crore. This creates an opportunity for CSR programmes to connect green skilling with existing women-led financial and community networks, instead of creating separate systems from scratch.The government’s SVEP model similarly supports rural entrepreneurs in setting up businesses and provides assistance until they become more stable. CSR can strengthen these existing systems by providing targeted support for green enterprises, helping women turn their skills into viable businesses, reliable incomes and long-term economic opportunities. Could Financial Inclusion Decide Whether Women Stay in the Green Economy?Access to finance can determine whether green-skills training leads to real economic independence. A woman may have the technical skills to provide solar maintenance or run a green enterprise, but without the money to purchase tools, equipment or basic business inputs, she may remain dependent on an employer. Access to small-business finance, on the other hand, can give her the opportunity to build and manage her own livelihood. But finance alone is not enough. Women also need access to markets. Providing loans without ensuring access to customers, procurement opportunities or business support can leave women with financial obligations but without a stable and sustainable source of income. This is where companies can use their own supply chains to create stronger opportunities. Large businesses in sectors such as construction, logistics, healthcare and education could create procurement opportunities for women-led enterprises providing solar maintenance, waste-management services, sustainable food supplies or energy-related solutions. Such an approach can move CSR from simply training women for employment to helping them build sustainable sources of income and participate in the wider green economy. Are Green Jobs Creating Better Work for Women?The quality of employment matters just as much as the number of women entering the green workforce. Green jobs are often presented as automatically better opportunities, but a job does not become a decent job simply because it is linked to renewable energy or sustainability. Women entering these sectors still need fair wages, safe workplaces, reasonable working conditions, effective grievance mechanisms and access to social protection. These factors also influence whether women remain in technical roles over the long term. If women leave their jobs within a few months because of low wages, unsafe working conditions or limited opportunities for career growth, a programme may appear successful on paper while failing to create lasting employment opportunities. Companies therefore need to look beyond job placements and understand what happens after women enter the workforce. Regular feedback and worker interviews, conducted independently and without management present, can help identify issues that may not appear in official programme reports - such as harassment, wage disputes, unsafe conditions, inadequate transport or difficulties accessing workplace benefits. The real measure of success is not simply whether women get green jobs, but whether those jobs provide the security, dignity and opportunity needed to build lasting livelihoods. What Should Companies Actually Measure? For women-focused green CSR programmes, measuring activities alone is not enough. The real test is whether those activities lead to meaningful and lasting improvements in women’s employment, income and economic opportunities. FROM TRAINING TO GREEN LIVELIHOOD  Women Enrolled↓Training Completed↓Job / Enterprise Started↓Wage or Business Income↓6–12 Month Retention↓Benefits + Grievance Access↓Career / Business GrowthCompanies should also report the starting point or baseline against which changes in income or employment are measured. If a programme reports an increase in women’s earnings, it should clearly establish their income levels before the intervention to demonstrate the actual change achieved. The same clarity is needed when reporting beneficiaries. For example, if an NGO trained 1,000 women, but only 400 completed the course and 180 found employment, these figures should be reported separately rather than combined into one broad “beneficiaries reached” number. Financial reporting should follow the same approach. Companies should clearly state: How much was budgeted? How much was actually spent? How much went towards training, equipment, job placement and support for women-led enterprises? Clear reporting of these numbers helps show the difference between a CSR announcement and a programme that is actually being implemented and creating results.So, Can Women Actually Lead India’s Green Economy?India’s green economy is opening up new opportunities for women, but participation alone will not be enough. The real opportunity lies in ensuring that women can enter the sector, build stable livelihoods and progress into roles with greater skills, responsibility and decision-making power. The clean-energy transition is creating a new employment landscape in India, but women are still underrepresented in the technical roles that will shape its future. CSR can help close this gap by connecting women with opportunities in renewable-energy technology, EV maintenance, sustainable agriculture and green enterprises. But the strongest programmes will not end when the training period does. Training must be the starting point - not the finish line. Its impact should continue through employment, fair wages, access to finance and markets, safe working conditions, social protection and opportunities for career progression. For companies, the real measure of success goes beyond training numbers.They need to ask whether women are earning more, staying employed, receiving workplace benefits and moving into higher-skilled and better-paid roles. For women, being part of the green workforce should only be the beginning. They should have opportunities to grow into technicians, entrepreneurs, supervisors and decision-makers who help shape India’s green future.India is preparing for a greener economy. The real CSR test is whether women are being given the skills, opportunities and support to lead it.Sources: CEEW–NRDC — Driving Energy Transition: Workforce, Skills, and Gender in India’s Renewable Energy Sector (https://www.ceew.in/publications/driving-energy-transition-workforce-skills-and-gender-in-indias-renewable-energy-sector) (CEEW)CEEW–NRDC — India’s clean energy targets could create over 44 lakh jobs by 2030 (https://www.ceew.in/press-releases/india%E2%80%99s-clean-energy-targets-could-create-over-44-lakh-jobs-2030-rooftop-solar) (CEEW)Ministry of New and Renewable Energy (MNRE) — Suryamitra Skill Development Programme (https://mnre.gov.in/en/skill-development-programme/) (Ministry of New and Renewable Energy)Ministry of Rural Development / PIB — DAY-NRLM and Self-Help Groups (https://www.pib.gov.in/PressReleasePage.aspx?PRID=2224571) (Press Information Bureau)Ministry of Rural Development / PIB — DAY-NRLM financial inclusion and SHG credit (https://www.pib.gov.in/PressReleasePage.aspx?PRID=2222697) (Press Information Bureau)Ministry of Rural Development / PIB — Start-up Village Entrepreneurship Programme (SVEP) (https://www.pib.gov.in/PressReleasePage.aspx?PRID=2205172) (Press Information Bureau)Ministry of Rural Development / PIB — Women-led enterprises and public procurement under DAY-NRLM (https://www.pib.gov.in/PressReleasePage.aspx?PRID=2229449) (Press Information Bureau)Ministry of Rural Development / PIB — DAY-NRLM outcomes and financial inclusion, 2026 (https://www.pib.gov.in/PressReleasePage.aspx?PRID=2287316) (Press Information Bureau) ...Read more

17 Aug 2026

Kolkata | 17 August 2026  As e-commerce and logistics companies electrify delivery fleets, the next challenge is building enough charging, battery-swapping and power infrastructure to keep the transition moving. SummaryIndia’s e-commerce and logistics sector is steadily shifting towards electric delivery vehicles as companies seek to reduce fuel costs and transport emissions. Amazon has already crossed its target of 10,000 electric delivery vehicles in India, while Flipkart has reported more than 13,000 EVs in its delivery ecosystem and is working towards a fully electric fleet by 2030. However, the transition involves more than replacing conventional vehicles with EVs. Commercial fleets also require dependable charging and battery-swapping infrastructure, adequate grid connections and careful management of electricity demand. As electric fleets expand across delivery hubs and logistics networks, the availability and capacity of supporting power infrastructure will become central to the success of India’s commercial e-mobility transition. Is India’s E-commerce Sector Ready to Electrify the Last Mile?  Every day, thousands of delivery vehicles carry parcels across Indian cities. These vehicles often follow fixed routes, return to warehouses or delivery hubs and operate for long hours, making last-mile logistics one of the areas where electric vehicles can be adopted at scale. The transition is already underway. Amazon India set a target of deploying 10,000 electric delivery vehicles by 2025 and reached that goal ahead of schedule. Flipkart has set a longer-term target of making its last-mile delivery fleet fully electric by 2030. The shift is also spreading beyond the country’s largest e-commerce companies. Electric mobility firms are supplying vehicles to quick-commerce platforms, food-delivery companies and logistics operators, expanding the market for electric two-wheelers, three-wheelers, vans and other commercial vehicles. But the size of an electric fleet alone does not show whether the transition is working or not. For an EV to be useful in commercial delivery, it must be able to complete its route, recharge within the required time and return to service without disrupting operations. That makes charging infrastructure one of the biggest challenges in India’s move towards electric last-mile delivery. What Happens When the Vehicle Is Ready but the Charger Isn’t? For a private EV owner, charging can usually be planned around personal schedules. For a commercial delivery fleet, however, charging directly affects business operations. Every hour a delivery vehicle spends waiting for a recharge is an hour it is not on the road making deliveries. The challenge becomes even greater when several vehicles return to the same warehouse or delivery hub around the same time, creating a sudden increase in electricity demand. This is why companies are gradually exploring dedicated fleet-charging hubs instead of relying entirely on public charging stations. Tata Power has been expanding its charging network across public, semi-public and fleet locations, while oil and energy companies are also becoming part of the growing EV-charging ecosystem. The wider transition involves companies such as NTPC, NTPC Green, Tata Power, Reliance New Energy, ReNew, Adani Green, Indian Oil and GAIL. Their roles vary from renewable power generation and electricity supply to charging infrastructure, energy storage and existing fuel-station networks - but they are connected to the same shift towards electric mobility. The last-mile EV transition, therefore, is no longer just about replacing petrol and diesel vehicles with electric ones. But also, about building the energy and charging infrastructure needed to keep those vehicles moving.Could Battery Swapping Help Delivery Fleets Stay on the Move?  Charging time matters even more for electric two- and three-wheelers that spend most of the day making deliveries. For these high-use vehicles, battery swapping can offer an alternative to conventional charging. Instead of waiting for a depleted battery to recharge, a delivery vehicle can exchange it for a fully charged one and get back on the road. Reliance’s Jio-bp has explored battery-swapping and Battery-as-a-Service models for electric mobility, while India’s policy framework has also started recognising battery swapping as part of the broader EV-charging ecosystem. For delivery companies, the benefit is clear: less time spent charging can mean more time making deliveries. However, battery swapping also creates new challenges. Companies will also need to address key questions around battery ownership and maintenance, compatibility across different vehicle models, the location of swapping stations and who will bear the cost of setting up and operating the network.  Without common standards and enough vehicles using the network, swapping stations may struggle to reach the scale needed to remain commercially viable. Battery swapping can help reduce charging downtime, but it does not remove the need for a strong and reliable infrastructure network. Instead, it shifts the focus from charging stations to a wider network of batteries, swapping points and supporting systems.  Could Faster Charging Put More Pressure on India’s Power Grid?  One of the less visible challenges of the EV transition is its growing impact on India’s electricity network. Electric vehicles reduce dependence on petrol and diesel, but they also shift transport energy demand from fuel stations to the power grid. For commercial delivery fleets, this shift can be particularly significant because vehicles often operate for long hours and need to recharge within tight schedules. A large delivery depot could have dozens or even hundreds of vehicles requiring power within a limited period. If several vehicles charge at the same time, the local distribution network could face a significant increase in demand. This does not necessarily mean that India’s power grid cannot support the growth of electric vehicles. The bigger issue is where, when and how that electricity is consumed. Smart-charging systems can shift charging to periods of lower electricity demand. Battery storage can help manage peak loads, while renewable energy can reduce the emissions associated with charging. Careful planning can also help companies avoid placing large charging facilities in locations where the local power network is already under pressure. The move towards electric delivery, therefore, cannot be managed by fleet operators alone. Companies and electricity providers will need to plan charging capacity together so that the growth of electric fleets does not create unnecessary pressure on the power system. Can India’s Commercial Freight Sector Make the Bigger Shift to Zero Emissions? Electrifying two- and three-wheelers may be relatively easier, but heavy commercial vehicles present a much bigger challenge. Electric trucks require larger batteries, higher-capacity charging systems and careful route planning to ensure they can cover long distances without disrupting delivery schedules. India is beginning to identify priority freight corridors for zero-emission trucking, with charging infrastructure being planned along major routes. Over time, this could help connect warehouses, logistics hubs and cities through dedicated electric freight networks. However, the financial and operational challenges of this transition cannot be overlooked. Companies will need to account for vehicle purchase costs, battery replacement, charging infrastructure, land requirements, grid connections, electricity tariffs and ongoing maintenance. For investors and corporate sustainability teams, therefore, the important question is not simply whether a company has announced a target for electric trucks. The real test is whether the company has the business model, infrastructure and financial capacity to achieve that target at scale. Could Renewable Energy Make Commercial EVs Even Cleaner?  The environmental benefits of commercial electric vehicles become stronger when the electricity used to charge them comes from renewable sources. In other words, the transition is not only about replacing petrol and diesel vehicles with EVs, but also about ensuring that the electricity powering those vehicles comes from cleaner sources.This is where India’s renewable-energy and power-sector companies have an important role to play. Companies such as NTPC Green, ReNew and Adani Green can contribute to the broader clean-energy ecosystem supporting electric transport, while Tata Power can help connect electricity supply with the charging infrastructure needed by commercial fleets.   The future may therefore involve a much more integrated system:   THE LAST-MILE ELECTRIFICATION CHAIN  Renewable electricity↓Grid & energy storage↓Charging / battery swapping↓Electric delivery fleet↓Zero-emission last-mile deliveries  The success of the transition depends on how well these different parts work together. A growing EV fleet needs sufficient charging capacity to operate smoothly, while charging infrastructure must be supported by proper grid planning to avoid new pressure on the electricity network. At the same time, powering electric vehicles with cleaner electricity can further increase their overall emissions benefits.  The EV Is Only the Beginning   The real test of India’s commercial EV transition will not be the number of targets companies announce. It will be the evidence they provide on what has actually changed.  A company promising a 100% electric fleet by 2030 has set a target. It has not yet achieved an outcome.   To show real progress, companies should disclose how many electric vehicles are currently in operation, what share of deliveries they handle, how many kilometres they travel and how much petrol or diesel use they have replaced. Charging infrastructure also needs to be measured by what it can actually deliver, rather than simply the number of stations announced or installed. Similarly, battery-swapping investments should be assessed through their actual use and operational performance. The financial picture matters too. Companies should clearly report the amount they committed to the transition, the amount actually spent, the number of EVs deployed, the charging capacity brought into operation, the baseline from which progress was measured and the changes achieved as a result.This evidence can help investors assess whether electrification is becoming an integral part of a company’s operations or remains largely a sustainability commitment on paper. The bigger question, then, is whether India can electrify its last-mile delivery network without creating new pressure on the systems that support it. The answer will depend not simply on how quickly companies purchase EVs, but on how effectively the wider ecosystem develops. India needs more electric vehicles, but it also needs well-planned charging hubs, reliable electricity connections, battery-swapping networks where they make economic sense and smart-charging systems that can manage peak demand. Most importantly, companies need to report what happened after the announcement. The case for electrifying commercial delivery is strong. These vehicles operate frequently, travel extensively through cities and account for significant fuel costs. Switching to EVs can help businesses reduce operating costs while also cutting local air pollution and transport-related emissions. But replacing a petrol or diesel vehicle with an electric one is only the beginning. The vehicle may be the most visible part of the transition, but it is supported by a much larger system of batteries, chargers, electricity networks, distribution infrastructure, renewable energy and investment. India’s e-commerce boom has already created the demand for this transition. Now the energy system has to build the capacity to support it. And that is the real story of India’s electric last mile: the shift may begin with an EV, but achieving genuinely lower emissions will depend on the entire system behind it - from batteries and charging infrastructure to the power grid and clean energy.   Primary sources  Amazon India — 10,000 EV milestoneSupports Amazon’s 10,000-EV target, its achievement ahead of schedule, deployment across 500 cities and its continuing work on electric heavy goods vehicles. Amazon India — 10,000 electric vehicles milestone Flipkart — Sustainability JourneySupports Flipkart’s 13,300 EVs and its commitment to 100% electric mobility by 2030. Flipkart — Building for tomorrow: sustainability journey Flipkart — EV Assist, June 2026Supports the current figure on delivery-partner adoption, including the 6,000+ delivery-partner study and 46% willingness to transition to EVs, as well as the 2030 ambition. Flipkart — EV Assist Tata Power — Integrated Annual Report 2025–26Supports the article’s discussion of commercial/fleet charging infrastructure, with 5,800+ public, semi-public and fleet charging points and 1,200+ e-bus charging points reported as operationalised. Tata Power — Integrated Annual Report 2025–26 Reliance Industries / Jio-bp — EV and battery-swapping initiativesSupports the claims about Jio-bp exploring battery swapping, Battery-as-a-Service and charging/swapping points, including applications for three-wheelers and commercial/last-mile mobility. Reliance — Jio-bp and Mahindra EV partnership Central Electricity Authority — EV Charging Station / Power Consumption ReportsThis is the key government source for the article’s grid and electricity-demand section. CEA maintains dedicated EV Charging Station/Power Consumption Reports as part of its energy-transition work. CEA — EV Charging Station / Power Consumption Reports Ministry of Power — EV Charging Infrastructure GuidelinesSupports the article’s discussion of charging infrastructure, grid-support requirements and fast charging for long-range/heavy-duty EVs. The guidelines specify fast-charging stations for heavy-duty vehicles at 100-km intervals on designated highways and call for supporting infrastructure such as transformers and feeders. Ministry of Power — EV Charging Infrastructure Guidelines WRI India — Electrifying India’s HighwaysSupports the section on electric freight and explains why e-truck charging requires high-capacity grid connections, larger sites and carefully planned electrical systems. WRI India — Electrifying India’s Highways WRI India — Accelerating India’s Freight DecarbonizationSupports the article’s discussion of electric freight, charging constraints, corporate adoption and the structural challenges facing zero-emission trucking. It currently reports 869 electric medium- and heavy-duty freight vehicles and identifies charging infrastructure and upfront costs as major barriers. WRI India — Accelerating India’s Freight Decarbonization WRI India — Fi-ZET: Financial Impact Assessment for Zero-Emission TrucksSupports the article’s discussion of the financial and operational feasibility of electric trucks, including vehicle costs, financing and route-specific economics. WRI India — Fi-ZET           ...Read more

10 Aug 2026

Kolkata | August 6, 2026 Climate-tech companies are beginning to deliver the kind of investor returns once reserved for mainstream technology start-ups. High-value private equity exits, founder wealth creation and employee stock payouts suggest India's green economy is entering a more mature phase. Yet behind the headline deals lies a more complex reality, although sustainability attracts unprecedented investment globally, many early-stage climate innovators still struggle to secure the capital they need. Quick SummaryIndia's climate-tech ecosystem is reaching an important milestone as sustainability-focused start-ups begin generating meaningful financial returns for investors, founders and employees. Successful private equity exits, strategic acquisitions and expanding ESOP wealth creation indicate that green businesses are gradually moving from experimental ventures to commercially viable enterprises capable of attracting institutional capital. These developments could strengthen investor confidence and encourage greater participation from banks, infrastructure funds, venture capital firms and green-bond issuers. However, beneath these success stories, early-stage climate-tech companies continue to face tightening funding conditions, higher investor expectations and longer fundraising cycles. As India's clean economy expands, the real challenge is ensuring that capital supports not only established winners but also the next generation of innovators developing technologies needed for the country's long-term climate transition. Are Climate-Tech Exits Creating a Stronger Green Investment Cycle? For years, climate-tech entrepreneurs faced a familiar question: Can sustainability generate attractive financial returns? Although investors recognised the long-term potential of sectors such as clean energy, battery recycling, carbon capture, green materials and circular manufacturing, many remained cautious about investing. Climate-tech businesses often require years of research, large upfront investments and supportive government policies before they become profitable, making them a riskier bet than many conventional technology start-ups.That perception is gradually changing.Across India, a growing number of climate-tech companies are moving beyond the experimental stage and proving that environmental innovation can also be commercially successful. High-value acquisitions, private equity exits and strategic investments are giving investors the returns they have been waiting for while rewarding founders who have spent years building businesses around the low-carbon economy. For venture capital and private equity firms, these deals represent far more than isolated success stories. Every successful exit strengthens confidence that climate-tech can become a profitable business. It shows that companies in the sector can grow, attract institutional buyers and generate competitive returns, encouraging more investors to back climate-focused innovation.The benefits are also reaching employees.Many professionals who joined climate-tech start-ups in their early years are now benefiting through Employee Stock Ownership Plans (ESOPs), turning years of equity ownership into real financial gains. In a sector long driven by purpose as much as profit, wealth creation is becoming an important sign of maturity. These success stories are also helping attract experienced professionals who may once have viewed climate-tech as a risky career choice. However, the headlines tell only part of the story. While a handful of established climate-tech companies are securing impressive valuations and rewarding investors, many younger start-ups continue to struggle to raise funding. Investors have become far more selective, preferring businesses that already have clear revenue streams, strong financial performance and a realistic path to profitability. As a result, many promising early-stage innovators are finding it difficult to secure the capital needed to grow. This reflects one of the biggest challenges facing India's green economy. If the wealth created through successful exits is reinvested across the broader climate-tech ecosystem, it could encourage new ideas, support emerging businesses and accelerate India's transition to a low-carbon economy. But if investment remains concentrated in a small number of mature companies, many promising innovators may never receive the support needed to develop the technologies that will drive India's future in clean energy, resource efficiency and net-zero development. The debate is therefore no longer about whether climate-tech can create economic value. The real question is whether today's success stories will generate enough fresh investment to support tomorrow's innovators and strengthen the ecosystem that made those achievements possible. From Climate Ambition to Commercial Returns India's climate-tech sector has changed dramatically over the past decade. What was once a niche investment space focused mainly on renewable energy has grown into a broad ecosystem of businesses working on electric mobility, battery technologies, sustainable materials, carbon management, resource efficiency and circular economy solutions. This growth has been fuelled by a combination of government support, rising investor confidence and increasing demand from businesses for low-carbon technologies. Policies promoting clean energy, electric vehicles and green manufacturing, together with India's net-zero commitment and growing ESG expectations, have encouraged companies to develop solutions that not only reduce environmental impact but also create long-term commercial value. As the sector has matured, the pattern of investment also evolved.In the early years, most climate-tech start-ups depended on angel investors, incubators and venture capital firms willing to back high-risk ideas. Today, many successful companies are attracting larger investors, including private equity firms, infrastructure funds, strategic corporate buyers and institutional investors. This shift reflects growing confidence that climate-tech can deliver strong and sustainable financial returns.For investors, a successful exit represents far more than the success of a single company. When a company is acquired or investors sell their stake, they recover their investment, demonstrate returns to their backers and free up capital to invest in the next generation of start-ups.  This recycling of capital is essential for keeping the innovation ecosystem healthy. Without successful exits, investors become more cautious, fundraising slows and fewer new businesses receive the support they need to grow.India is beginning to see the benefits of this cycle.Large infrastructure investors, climate-focused funds and financial institutions are treating green businesses as long-term investment opportunities rather than experimental ventures. Organisations such as IREDA continue to expand financing for renewable energy and clean technology projects, while SIDBI Venture Capital is strengthening support for innovation-driven enterprises. Alongside them, specialised climate funds and impact investors are broadening the range of financing available for businesses working on decarbonisation, sustainable manufacturing and resource efficiency.The country's expanding green finance market is also playing an important role. Green bonds, sustainability-linked loans and ESG-focused investment products are opening new funding channels and attracting larger pools of institutional capital. Banks, non-banking financial companies (NBFCs) and infrastructure funds are gradually evaluating climate-tech businesses not only for their environmental benefits but also for their commercial potential and long-term resilience. While the sector has made significant progress, important hurdles remain.  While established climate-tech companies are attracting larger investments and delivering successful exits, many younger start-ups continue to struggle to raise funding. Investors have become more selective, favouring businesses with proven revenues, efficient operations and a clear path to profitability. As a result, many promising start-ups are finding it difficult to secure the funding needed to develop and expand their technologies. This growing gap raises an important question. If successful exits are creating wealth and attracting new investors, how can India ensure that enough of this capital reaches the next generation of climate innovators who will drive the country's future green economy?   The Climate-Tech Capital Cycle Innovation → Seed Funding → Series A/B Growth Capital → Scale-Up → Private Equity / Strategic Investment → Exit → Capital Reinvested into New Climate Start-ups Key takeaway: Successful exits do more than reward investors- they recycle capital back into the innovation ecosystem. The Exit Economy: When Green Innovation Starts Delivering Returns For venture capital and private equity investors, a successful exit is more than a profitable deal- it is a sign that an industry has reached a new level of maturity. Climate-tech companies have traditionally taken longer to grow than conventional technology start-ups. Many require significant investment, years of research and supportive regulations before becoming commercially successful. Because of this, investors often had to wait much longer to see returns. Today, however, successful acquisitions, private equity exits and secondary sales are changing that picture, showing that businesses built around sustainability can generate strong financial returns alongside environmental impact. These success stories are boosting investor confidence. Institutional investors are viewing climate-tech as a promising long-term investment rather than a niche sustainability sector. Large transactions in renewable energy, electric mobility, battery technology, climate software and sustainable materials are encouraging infrastructure funds, pension-backed investors and growth capital firms to increase their exposure to India's green economy. The gains are not limited to investors and founders. Employees who joined climate-tech companies in their early years are also beginning to benefit through Employee Stock Ownership Plans (ESOPs), turning years of equity ownership into significant financial rewards. These outcomes are helping attract experienced engineers, scientists, sustainability professionals and business leaders who may once have considered climate-tech too risky as a long-term career choice. For entrepreneurs, successful exits carry equal importance. They validate years of innovation, business development and investor confidence, proving that sustainability-focused businesses can scale successfully while delivering meaningful environmental solutions.  Many founders who achieve successful exits also go on to become angel investors or mentors, using their experience and capital to support the next generation of climate-tech start-ups. However, these encouraging developments reveal only one side of the story. While established climate-tech companies are attracting larger investments and delivering strong investor returns, many younger start-ups continue to face a difficult fundraising environment. Investors are becoming selective, favouring businesses with stronger revenues, clear business models and a faster path to profitability. As a result, many early-stage companies developing new technologies are finding it harder to secure the funding needed to grow. This has created an uneven investment landscape. A small number of mature companies are generating impressive returns, while many promising start-ups continue to struggle for early-stage funding. Industry experts warn that if investment remains concentrated only in established businesses, India could slow the development of the next generation of technologies needed to support its long-term decarbonisation and sustainability goals. Successful exits, therefore, are only part of the story. They prove that climate-tech can create both environmental impact and financial value. But the long-term strength of the sector will depend on whether today's returns are reinvested in the innovators building tomorrow's clean technologies. Where the Returns Go Successful Climate-Tech Exit ⬇ ✔ Investors recover capital ✔ Employees benefit through ESOPs ✔ Founders gain liquidity ✔ Confidence in climate-tech grows ✔ Fresh capital flows into future ventures Key takeaway: Every successful exit has the potential to finance the next generation of climate innovation- but only if capital continues moving downstream.  Beyond the Headlines: Are Green Returns Reaching the Next Generation of Innovators? The recent wave of climate-tech exits has strengthened confidence in India's green economy. However, experts caution that headline valuations and high-profile deals alone do not reflect the true health of the sector.Every successful acquisition or investor exit marks the end of one investment journey. The bigger question is whether the money generated from these deals is being reinvested in the next generation of climate-tech start-ups or remaining concentrated in a small number of established companies. Research organisations such as the Council on Energy, Environment and Water (CEEW), Climate Policy Initiative India (CPI India) and WRI India have consistently pointed out that achieving India's climate and net-zero goals will require steady investment at every stage of innovation. This includes everything from early research and product development to large-scale commercial deployment. In other words, a strong climate-tech ecosystem depends not only on successful exits but also on a continuous flow of funding for new ideas and emerging businesses. This is where the funding gap becomes more visible. While investors continue to announce ambitious climate commitments, much of the available capital is flowing towards companies with proven business models and stable revenues. Early-stage start-ups working on technologies such as green materials, carbon removal, industrial decarbonisation and advanced battery solutions often face longer fundraising periods and greater difficulty attracting investment, despite their long-term importance. For policymakers, the challenge is not simply attracting more investment but ensuring that it reaches the right parts of the ecosystem. Institutions such as the Reserve Bank of India (RBI), SEBI, IREDA, SIDBI and the Ministry of Finance are gradually strengthening India's sustainable finance ecosystem through green bonds, climate-focused lending and improved disclosure frameworks. However, experts argue that financing must support innovation as much as infrastructure if India hopes to remain a leader in climate technology. Looking beyond headline numbers is therefore essential. A large investor exit may signal growing confidence in the sector, but it does not tell the complete story. Analysts believe that market performance should also be assessed through transparent reporting, realistic valuations and clear distinctions between announced investments and capital that has actually been deployed. Such disclosures provide a more accurate picture of the sector's long-term growth. Transparency is equally important. Large funding announcements often make headlines, but less attention is given to how that capital is used, how projects perform over time or whether they deliver meaningful environmental outcomes. Experts believe that stronger disclosure around investment deployment, technology adoption and measurable impact would help investors identify businesses creating lasting value rather than short-term optimism. Ultimately, the future of India's climate-tech sector will not be defined by the size of a few high-profile exits alone. Its long-term success will depend on whether today's financial gains help fund tomorrow's innovators, ensuring that investment continues to support not only companies already delivering returns but also those developing the technologies that will power India's low-carbon future.   Evidence Check Evidence TestWhat Investors Should AskMethodologyHow was the valuation calculated?Peer BenchmarkHow does the company compare with similar climate-tech firms?Implementation GapWas announced investment fully deployed?BaselineWhat was the company's starting scale before investment?Reporting BoundaryAre only financial returns measured, or environmental impact too?Capital DeploymentHow much funding actually reached projects?Long-Term ValueDoes the exit strengthen future climate innovation? Key takeaway: A successful exit proves commercial viability-but a healthy climate-tech ecosystem is measured by how effectively capital is reinvested into future innovation. The Road AheadClimate-tech has reached an important turning point.Not long ago, many green start-ups depended on bold ideas, supportive policies and investors willing to wait years for returns. Today, that picture is changing. A growing number of successful exits show that businesses built around sustainability can create real financial value while helping address environmental challenges. They also reflect a more mature ecosystem where climate-focused companies are attracting institutional investors, rewarding founders and creating wealth for employees through ESOPs. But a few high-profile success stories alone cannot define the future of the sector. For India's climate-tech ecosystem to remain strong, investment must continue across the entire innovation journey- from research labs and early-stage start-ups to companies ready for large-scale commercial growth. If funding keeps flowing only to businesses that have already proven themselves, many promising ideas may never reach the market. The real success of climate-tech will not be measured only by billion-dollar exits or investor returns. It will depend on whether today's gains help build tomorrow's innovators. If the capital generated through successful exits is reinvested into the next wave of entrepreneurs, India will not only strengthen its green economy but also accelerate the development of technologies needed for a cleaner and, a more sustainable future. Evidence Check Evidence TestStatusMethodology disclosedVaries across transactionsExit completed or announcedMust be independently verifiedPeer benchmark availableEssential for valuation comparisonCapital actually deployedMore important than commitments announcedESOP wealth disclosedLimited public reportingLong-term reinvestmentKey indicator of ecosystem maturity Key Takeaways:Climate-tech exits are validating India's green innovation ecosystem.  Private equity returns can attract the next wave of sustainable investment.  ESOP payouts are creating wealth and attracting talent to climate ventures.  Early-stage funding remains significantly tighter than growth-stage capital.  Long-term ecosystem strength depends on reinvesting today's returns into tomorrow's climate innovators.  Expert SnapshotCEEW: Climate innovation requires sustained investment across the entire technology lifecycle.  Climate Policy Initiative India: Long-term climate finance must support both infrastructure and innovation.  IEEFA South Asia: Strong capital flows are essential, but funding must remain diversified across emerging technologies.   Sources: Securities and Exchange Board of India (SEBI) – ESG disclosures, sustainable finance and capital marketshttps://www.sebi.gov.in/ Reserve Bank of India (RBI) – Climate risk, sustainable finance and financial stability reportshttps://www.rbi.org.in/ Ministry of Finance, Government of India – Green finance and economic policy updateshttps://finmin.gov.in/ Indian Renewable Energy Development Agency (IREDA) – Annual Reports, project financing and renewable energy lendinghttps://www.ireda.in/ Small Industries Development Bank of India (SIDBI) – Venture Capital and MSME innovation financinghttps://www.sidbi.in/ Council on Energy, Environment and Water (CEEW) – Climate-tech investment, energy transition and clean economy researchhttps://www.ceew.in/ Climate Policy Initiative (CPI) India – Climate finance reports and investment analysishttps://www.climatepolicyinitiative.org/ WRI India – Climate innovation, sustainable finance and energy transition researchhttps://wri-india.org/ IEEFA South Asia (Institute for Energy Economics and Financial Analysis) – Clean energy investment and financial market analysishttps://ieefa.org/ Rainmatter Foundation – Climate innovation grants and ecosystem supporthttps://rainmatter.org/ Climate Collective Foundation – Indian climate-tech ecosystem and start-up support initiativeshttps://climatecollective.net/ Baring Private Equity Partners India (now part of EQT) – Private equity investment insights and portfolio informationhttps://eqtgroup.com/     ...Read more

01 Aug 2026

As India pushes sustainable aviation fuel to cut aviation emissions, questions over feedstocks, costs and competition for land and food are beginning to shape the debateKolkata| August 1, 2026: The future of aviation may depend not only on how aircraft are designed, but also on what powers them.Today, aviation contributes around 2–3% of global carbon dioxide emissions, and unlike road transport, long-distance flights still have limited alternatives to conventional liquid fuels. As governments and airlines look for ways to reduce emissions without disrupting air travel, Sustainable Aviation Fuel (SAF) has emerged as one of the sector's most promising solutions. For India, adopting Sustainable Aviation Fuel is not simply a question of replacing one fuel with another. It requires balancing climate ambitions with economic viability, feedstock availability and long-term sustainability. SAF is produced from renewable or waste-based feedstocks instead of conventional crude oil. Depending on the production pathway, it can substantially reduce lifecycle greenhouse gas emissions while remaining compatible with existing aircraft engines and airport infrastructure. Its compatibility with existing aircraft engines and airport infrastructure makes SAF one of the most practical and scalable solutions for reducing aviation emissions. India is gradually bringing Sustainable Aviation Fuel into the centre of its clean energy and climate strategy.Government agencies, airlines, oil marketing companies and research institutions are working to expand domestic production, support pilot projects and prepare for future blending mandates.Beyond reducing aviation emissions, these efforts are intended to strengthen energy security and help India secure a place in the emerging global SAF market. The real challenge, however, extends beyond policy ambition. It lies in ensuring a sustainable and reliable supply of feedstock that can support production on a commercial scale. Experts point to agricultural residues, used cooking oil, municipal solid waste, forestry waste and certain non-food energy crops as the most promising sources for Sustainable Aviation Fuel. Unlike food-based feedstocks, these resources can help reduce emissions without affecting food security. The challenge, however, lies in building efficient supply chains, as collecting, transporting and processing these materials remains expensive and operationally complex. The conversation becomes far more complex when cleaner fuel begins to compete with food and land resources. Using edible oils, sugar crops or fertile agricultural land as feedstocks could place additional strain on food prices, water availability and rural livelihoods. Environmental experts also warn that clearing forests or natural ecosystems to cultivate energy crops may erode many of the climate gains that Sustainable Aviation Fuel seeks to achieve. As a result, the real challenge is not simply producing cleaner aviation fuel- it is ensuring that the path to cleaner aviation does not create new environmental or social pressures along the way.  Cost remains one of the biggest hurdles for Sustainable Aviation Fuel. Production volumes are still limited, supply chains are yet to mature and, as a result, SAF continues to cost significantly more than conventional jet fuel. For airlines already operating in a highly competitive market with narrow profit margins, absorbing these additional costs will not be easy without targeted policy support and market incentives. That is why the design of future blending mandates could determine how quickly SAF moves from ambition to widespread adoption. Rather than imposing immediate large-scale adoption, many countries are introducing phased blending mandates that gradually expand the use of Sustainable Aviation Fuel while supporting domestic production and maintaining industry competitiveness. Experts argue that India will need a similar approach—one that balances climate commitments with commercial realities and gives producers, refiners and airlines the certainty and time needed to expand investments, production capacity and supporting infrastructure.Despite these challenges, experts emphasise that Sustainable Aviation Fuel is only one part of the solution. Reducing aviation emissions will also depend on more fuel-efficient aircraft, improved air traffic management, operational efficiencies and the development of future technologies such as hydrogen-powered aircraft. The future of aviation decarbonisation won’t rest on SAF alone. It will sit alongside efficiency, new aircraft, and operational changes. For India, Sustainable Aviation Fuel represents more than an alternative fuel- it offers an opportunity to reshape the future of cleaner aviation. A successful SAF ecosystem could create economic value from agricultural waste, strengthen energy security, encourage innovation and help the country move closer to its climate commitments. But lasting success will depend on ensuring that the transition protects food security, safeguards ecosystems and supports the communities that depend on them. The future of aviation will not be judged only by how much it reduces emissions, but by how responsibly it achieves that transition. Because sustainable flight truly begins long before it’s take-off - with fuel that is as sustainable in its production as it is in its purpose. Sources: International Civil Aviation Organization (ICAO) – SAF Feedstocks (CORSIA Framework)https://www.icao.int/CORSIA/feedstocksInternational Civil Aviation Organization (ICAO) – Guidance on Policy Measures for SAF Development and Deploymenthttps://www.icao.int/SAF/saf-guidance-policy-measuresInternational Civil Aviation Organization (ICAO) – SAF Rules of Thumb (Feedstocks, Costs & Production Pathways)https://www.icao.int/SAF/saf-rules-of-thumbICAO ACT-SAF Programme – India Sustainable Aviation Fuel Feasibility Studyhttps://www.icao.int/sites/default/files/environmental-protection/Documents/ACT-SAF/Feasibility_Study_India.pdfInternational Air Transport Association (IATA) – Global Feedstock Assessment for SAF Production Outlook to 2050https://www.iata.org/globalassets/iata/publications/sustainability/global-feedstock-assessment-for-saf-production-outlook-to-2050.pdfMinistry of Petroleum and Natural Gas (Government of India) – Biofuels and Sustainable Aviation Fuel policy updateshttps://mopng.gov.in/Ministry of Civil Aviation (Government of India) – Aviation sustainability initiatives and SAF developmentshttps://www.civilaviation.gov.in/NITI Aayog – Reports on biofuels, energy transition and low-carbon transporthttps://www.niti.gov.in/International Energy Agency (IEA) – Aviation and Sustainable Fuelshttps://www.iea.org/Down To Earth – Coverage on SAF, biofuels, feedstock availability and food-versus-fuel concerns in Indiahttps://www.downtoearth.org.in/ ...Read more

01 Aug 2026

As pumped storage gains momentum across India, debates over land, ecology, financing and cleaner alternatives are growing alongside it KOLKATA | August 1, 2026: India's renewable energy capacity is expanding rapidly, but the next phase of the transition will depend on solving a critical challenge: storing clean electricity when renewable sources are not generating power. Pumped storage hydropower (PSH) has emerged as one of the country's most promising solutions and is now playing a central role in India's energy planning. However, as projects begin moving from policy announcements to on-ground development, they are also raising important questions about land, ecology, financial viability and whether alternative storage technologies can deliver the same benefits with fewer trade-offs. Pumped storage hydropower functions like a giant rechargeable battery. Surplus electricity is used to pump water from a lower reservoir to an upper one, where it is stored until demand rises. When additional power is required, the water is released back through turbines to generate electricity. Its ability to provide long-duration energy storage and stabilise the electricity grid has made pumped storage an important part of India's strategy for integrating larger amounts of solar and wind power. Pumped storage hydropower is emerging as a cornerstone of the Union government's long-term clean energy strategy. Across states such as Maharashtra, Andhra Pradesh, Madhya Pradesh, Odisha and Karnataka, a growing pipeline of projects is expected to play a vital role in integrating larger volumes of solar and wind power into the grid. Yet as development gathers pace, the conversation is expanding beyond energy storage to include questions of land, ecology, financial viability and sustainability. While pumped storage offers important benefits for the power sector, many proposed projects are located in ecologically sensitive hilly and forested areas. Developing two reservoirs often requires significant land acquisition and extensive civil works. Experts caution that large-scale construction, forest diversion and changes to natural drainage systems could have lasting impacts on biodiversity, wildlife movement and local ecosystems. In many regions, residents have also expressed concerns about displacement, water availability and the long-term effects on their livelihoods. Financial sustainability is another issue shaping the debate. The financial challenge begins long before a pumped storage project starts generating electricity. While these facilities can operate for decades with relatively low operating costs, they demand substantial upfront investment and long construction timelines. Delays in environmental clearances, land acquisition or financing can sharply increase costs and affect overall project viability. Developers also need reliable revenue mechanisms that recognise the value of energy storage and grid-balancing services, rather than compensating only for electricity generation. These constraints have led to a broader discussion on whether alternative storage technologies could offer faster or more flexible solutions.Battery Energy Storage Systems (BESS) are emerging as a promising alternative, with declining costs and faster deployment making them well suited for a wide range of energy storage applications.Yet experts believe each technology serves a different purpose. While batteries perform well for short-duration storage, pumped storage hydropower remains better suited for storing large amounts of electricity over longer periods. Other solutions, including green hydrogen and advanced battery technologies, are also making steady progress, but they are still some ways from delivering the scale and reliability needed to support India's national electricity grid. Experts argue that pumped storage and batteries should be viewed as complementary rather than competing technologies. As renewable energy expands, India's electricity system is expected to require a combination of storage solutions capable of meeting different grid requirements. At the same time, policymakers face a broader challenge. Future projects will need rigorous environmental assessments, transparent engagement with local communities, fair compensation frameworks and stronger ecological safeguards to support both sustainable development and investor confidence. As India's renewable energy capacity continues to grow, pumped storage hydropower is expected to play a defining role in keeping the power system reliable. But its legacy will not be determined by storage capacity alone. It will be defined by whether development can balance environmental responsibility, financial sustainability and public trust alongside the country's growing energy needs.In the years ahead, the clean energy transition will be judged not only by how much renewable electricity India generates, but by how responsibly it chooses to store it. Sources: Ministry of Power, Government of India – Pumped Storage Projects Guidelines & Policy Initiativeshttps://powermin.gov.in/ Central Electricity Authority (CEA) – National Electricity Plan (Volume II: Transmission & Energy Storage)https://cea.nic.in/ NITI Aayog – Energy Storage Roadmap for Indiahttps://www.niti.gov.in/ International Energy Agency (IEA) – Electricity Storage & Hydropower Analysishttps://www.iea.org/ International Hydropower Association (IHA) – Pumped Storage Hydropowerhttps://www.hydropower.org/ Central Electricity Authority (CEA) – Status of Pumped Storage Projects in Indiahttps://cea.nic.in/hydro/ Down To Earth – Reports on pumped storage projects, environmental clearances and ecological concerns in India.https://www.downtoearth.org.in/ Mongabay India – Coverage of pumped storage projects, biodiversity impacts and community concerns.https://india.mongabay.com/ The Hindu BusinessLine – Coverage on pumped storage investments, project financing and renewable integration.https://www.thehindubusinessline.com/ Ministry of Environment, Forest and Climate Change (MoEFCC) – Environmental clearance notifications and project approvals.https://moefcc.gov.in/ ...Read more

31 Jul 2026

Kolkata | July 29, 2026  Kolkata-Based Mercstone Unveils Electric Scooter, Announces ₹250 Crore EV Manufacturing Investment In one of the most significant Indo–Thai manufacturing collaborations in India's rapidly expanding electric mobility sector, Kolkata-headquartered Mercstone International Pvt. Ltd. (Mercstone EV) and Assara Electric Company Ltd., Thailand, on Wednesday announced a strategic partnership to manufacture electric scooters in India through a proposed phased investment of nearly ₹250 crore. The first manufacturing facility will be established in West Bengal as part of the companies' long-term pan-India expansion strategy. On the occasion, the company's flagship electric scooter was formally unveiled in the presence of Dr Swapan Dasgupta, Hon'ble Minister of Finance, Shri Arjun Singh, Hon'ble Minister-in-Charge, Department of Labour & Transport, Government of West Bengal, along with senior government officials, industry leaders and an international business delegation. The collaboration marks the beginning of a long-term Indo–Thai partnership aimed at building an integrated electric mobility manufacturing ecosystem in India. Under the partnership, Assara Electric Company Ltd. will provide advanced technology, technical know-how and critical raw materials, while Mercstone International Pvt. Ltd. will establish the manufacturing infrastructure, complete production facilities, skilled manpower, and oversee all manufacturing, operations, marketing, sales and after-sales support across India. The proposed venture will focus on the manufacturing, assembly and distribution of next-generation electric scooters while developing a comprehensive ecosystem comprising component suppliers, technology partners, dealerships, service centres and logistics networks across the country. The project is expected to generate substantial direct and indirect employment opportunities as manufacturing capacity expands in phases. The investment comes at a time when India is accelerating its transition towards electric mobility under its sustainability agenda. The collaboration is expected to strengthen industrial cooperation between India and Thailand through technology transfer, advanced manufacturing, product development and innovation, while supporting India's vision of becoming a global hub for clean mobility manufacturing. Mercstone International Pvt. Ltd., incorporated in 2020, has already established a manufacturing and warehousing facility near the Kalyani Expressway at Barrackpore and has identified an additional location at Nabarand for future expansion. The company plans to scale manufacturing capacity progressively to meet growing demand across India. Its product portfolio will feature smart connected electric scooters equipped with Bluetooth-enabled vehicle tracking, IoT-based anti-theft systems, smartphone integration, keyless start, digital instrumentation, Lithium Iron Phosphate (LFP) battery technology, an Electronic Assisted Braking System (EABS), waterproof motors and advanced thermal management systems. As part of its national growth strategy, Mercstone EV will establish a robust dealership, distribution and after-sales service network across India to ensure seamless customer support and long-term product reliability. Looking ahead, the promoters plan to diversify into electric four-wheelers within the next five years, targeting an annual turnover of ₹500–700 crore while steadily expanding their manufacturing footprint and product portfolio. Industry observers believe the Mercstone–Assara partnership represents an important milestone in strengthening India's electric vehicle manufacturing ecosystem by combining international technology with Indian production capabilities. With India's EV market poised for sustained growth over the coming decade, the collaboration aims to contribute significantly to the country's clean mobility ambitions while enhancing India's position as a competitive global manufacturing destination. Tathagata Mukherjee,Director, Mercstone International Pvt. Ltd. «"This is not merely the launch of a new electric vehicle company; it marks the beginning of a strategic Indo–Thai manufacturing partnership with India at its core. Our proposed ₹250-crore phased investment reflects our long-term commitment to building world-class electric mobility solutions in India. Together with Assara Electric, we aim to create a strong manufacturing ecosystem, generate employment, strengthen the domestic vendor network and contribute meaningfully to India's vision of becoming a global clean mobility manufacturing hub."» Sandip Ghosh, General Manager, Mercstone International Pvt. Ltd. «"This partnership brings together the complementary strengths of both organisations. Assara Electric will provide advanced technology, technical expertise and critical raw materials, while Mercstone International will establish the complete manufacturing infrastructure, production facilities, skilled manpower and manage all manufacturing, operations, marketing and customer support in India. Together, we are committed to delivering technologically advanced, reliable and affordable electric mobility solutions backed by a strong nationwide dealership and after-sales network."» Assara Electric Company Ltd., Thailand «"India has emerged as one of the world's most promising electric vehicle markets, offering tremendous opportunities for innovation and manufacturing. Through our partnership with Mercstone International, we are bringing together Thai technology and Indian manufacturing excellence to develop world-class electric mobility solutions. We believe this collaboration will further strengthen industrial ties between Thailand and India while creating products capable of competing successfully in both domestic and international markets."» About Mercstone International Pvt. Ltd. Mercstone International Pvt. Ltd., headquartered in Kolkata, develops and manufactures smart, sustainable and affordable electric mobility solutions. The company is building an integrated pan-India ecosystem encompassing advanced manufacturing, technology, dealerships, distribution and after-sales services. About Assara Electric Company Ltd. Assara Electric Company Ltd., Thailand, specialises in electric mobility technologies, advanced manufacturing systems and EV components. Under the strategic partnership, the company will provide up technology, technical expertise and key raw materials to support the development of globally competitive electric vehicles for the Indian and international markets. This version is suitable for circulation to the media and follows standard corporate press release style with clearer role allocation, stronger flow and consistent terminology. Indo–Thai EV venture announces proposed ₹250-crore phased investment as Mercstone International and Thailand's Assara Electric forge strategic manufacturing partnership. Smt Papiya Adhikari, Hon'ble Member of Legislative Assembly, West Bengal unveiled the newly launched Infrared Cooktop. This Cooktop is a brand-new innovation to reduce electric consumption and introduce a better and smarter way of cooking. It can be used with every type of utensils of our daily household chores.  Dr Rajesh Kumar, Hon'ble Member of Legislative Assembly was also present at the event. ...Read more

31 Jul 2026

India is generating more clean energy than ever before. The next challenge is ensuring it can be stored, transmitted and delivered when it matters most     KOLKATA | JULY 31,2026India is making notable strides in its renewable energy transition. The expansion of solar parks, the growth of wind energy projects, and the steady increase in non-fossil fuel capacity highlight the country's progress toward its climate commitments. At the same time, another fundamental question is coming into sharper focus. Can India's electricity grid and energy storage systems keep pace with the rapid expansion of renewable power? The answer will play a decisive role in determining whether India's clean energy ambitions are matched by a resilient electricity system or limited by inadequate grid and storage capacity. India has made substantial progress in scaling up its non-fossil electricity capacity through sustained investments in solar, wind, hydropower, and nuclear energy. As a result, the country is steadily advancing toward its target of 500 GW of non-fossil capacity by 2030 while emerging as one of the fastest-growing renewable energy markets globally. The greater challenge, however, lies beyond generation- it is ensuring that the grid and energy storage systems can efficiently integrate and deliver this growing supply of clean power. While renewable energy capacity continues to expand, its effective utilisation remains a major challenge. Solar generation declines after sunset, and wind power fluctuates with changing weather conditions. For clean electricity to be available whenever and wherever it is needed, sufficient energy storage and a resilient transmission network are essential. Consequently, the focus of India's energy transition is shifting from merely generating renewable power to integrating it efficiently into the electricity system. As the share of renewable energy grows, the role of Battery Energy Storage Systems (BESS), pumped hydro storage projects, and modern transmission networks becomes critical. These technologies provide the flexibility required to store excess electricity, balance demand and supply, and maintain grid stability despite the intermittent nature of solar and wind power. Recent policy initiatives indicate a growing shift towards strengthening these enabling infrastructures alongside renewable energy expansion. Recognising the need for stronger supporting infrastructure, the government has announced large-scale battery storage programmes, accelerated interstate transmission projects, and encouraged investments in flexible power systems. Several states are also co-locating energy storage facilities with new renewable energy parks, reflecting an understanding that future electricity systems must expand generation, storage, and transmission in tandem. Even with these initiatives, critical gaps continue to hinder the pace of the transition. However, the transition is far from complete. Many energy storage projects remain in the pipeline, and utility-scale battery systems continue to be costlier than conventional power alternatives. Transmission infrastructure, too, has struggled to keep pace with the rapid growth of renewable energy, especially where large solar and wind projects are situated far from major demand centres. The expansion of storage and transmission infrastructure is further constrained by delays in land acquisition, regulatory approvals, and access to finance. At the same time, integrating increasing volumes of renewable energy into the national grid requires accurate forecasting, real-time digital monitoring, and smarter grid management technologies. The consequences of these challenges extend beyond the electricity sector, influencing energy security, industrial competitiveness, and the pace of India's broader low-carbon transition. Reliable renewable electricity is becoming the foundation of India's next-generation industries. Clean manufacturing depends on a dependable supply of low-carbon power, electric mobility requires a stable electricity network, and green hydrogen production demands uninterrupted renewable energy. Without sufficient storage capacity and modern transmission infrastructure, these sectors could struggle to realise their full potential despite the country's growing renewable energy capacity. For this reason, experts increasingly argue that India's clean energy transition must now be judged not only by the number of megawatts it adds, but by its ability to build an integrated, resilient, and flexible energy ecosystem capable of delivering clean power whenever and wherever it is needed. Meeting the next phase of the energy transition will require more than expanding renewable generation. It demands greater investment in domestic battery manufacturing, faster development of pumped hydro storage, modernised grid infrastructure, wider deployment of smart grid technologies, and increased private-sector participation in energy storage. Equally vital is effective coordination among central agencies, state utilities, and renewable energy developers to accelerate project execution and strengthen grid reliability. For consumers, the impact of these measures may not be immediately visible. Over time, however, they will translate into fewer power disruptions, a more dependable electricity supply, stronger support for low-carbon industries, and the ability to deliver clean energy generated during the day whenever demand is highest. As India approaches its 2030 renewable energy targets, the real challenge is no longer generating more clean electricity-it is ensuring that every unit of that electricity can be stored, transmitted, and delivered reliably. The next chapter of the energy transition will be written not in solar parks or wind farms alone, but in batteries, transmission corridors, and smarter electricity grids. In the end, India's clean energy future will not be defined by the scale of its renewable capacity, but by the strength of the infrastructure that supports it. Because renewable energy fulfils its promise only when clean power is available - not just when it is generated, but whenever and wherever it is needed. Sources:  Ministry of New and Renewable Energy (MNRE) – Energy Storage Systems (ESS) Overview (https://mnre.gov.in/en/energy-storage-systemsess-overview/)Ministry of New and Renewable Energy (MNRE) – Energy Storage Systems Technical Reports (https://mnre.gov.in/en/document-category/energy-storage-systemsess-technical-reports/)Central Electricity Authority (CEA) – Integrated Resource Planning (https://cea.nic.in/integrated-resource-planning-division/?lang=en)Central Electricity Authority (CEA) – National Electricity Plan (Generation) (https://cea.nic.in/integrated-resource-planning-division/?lang=en)Ministry of New and Renewable Energy (MNRE) – State Resource Adequacy Planning (https://mnre.gov.in/en/state-resource-adequacy-planning/)Ministry of Power, Government of India (https://powermin.gov.in/)Press Information Bureau (PIB), Government of India (https://pib.gov.in/)NITI Aayog – India's Energy Storage Mission: A Make-in-India Opportunity for Globally Competitive Battery Manufacturing (https://mnre.gov.in/en/document-category/other-reports/)International Energy Agency (IEA) – India Energy Outlook (https://www.iea.org/countries/india)International Renewable Energy Agency (IRENA) (https://www.irena.org/) ...Read more